Summary
Diesel is 80% of a travel center's revenue and about 30% of its gross margin. The freight recession is over on rates and barely over on volume, diesel set a $6.29 record in September, and the three national chains now set the pump price on every interstate corridor. This report sets out where the industry stands in October 2026, what a single site earns, how the loans perform, and how a feasibility study should underwrite a travel center that will still be paying its mortgage in 2051.
44 minute read.
Diesel is 80% of a travel center's revenue and about 30% of its gross margin. The freight recession is over on rates and barely over on volume, diesel set a $6.29 record in September, and the three national chains now set the pump price on every interstate corridor. This report sets out where the industry stands in October 2026, what a single site earns, how the loans perform, and how a feasibility study should underwrite a travel center that will still be paying its mortgage in 2051.
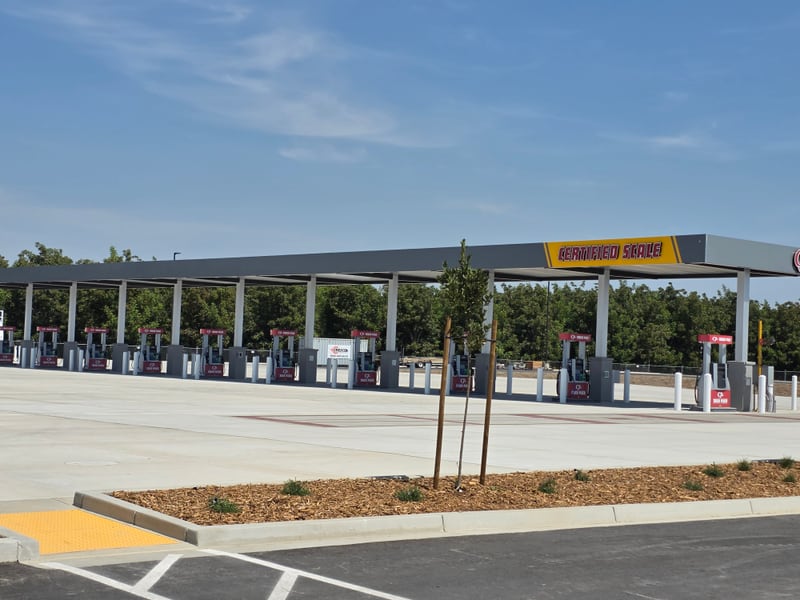
A truck stop is the only retail format in America that sells its anchor product at a margin set by someone else. A family-owned travel center at a rural interchange buys diesel at rack, sells it at a price its nearest Pilot or Love's has already posted, and clears somewhere between 16 and 25 cents a gallon after the fleet card has taken its discount. On a good site that is 7,000 to 9,000 gallons a day and a fuel gross profit that pays the light bill. What pays the mortgage is everything inside the fence line: the restaurant, the store, the showers, the truck bays, the parking and, in a handful of states, the slot machines.
That inversion is the organizing fact of the industry, and it is the one most feasibility studies get backwards. In TravelCenters of America's last audited year as a public company, fuel was 80.3% of revenue and roughly 31% of gross margin, while non-fuel revenue of $2.1 billion carried a 60.4% margin and produced the other two-thirds (1). A study that sizes a travel center on gallons has sized the wrong business.
The 2026 backdrop makes the point sharper. Truckload rates have recovered because capacity left the market, not because freight came back. Diesel demand is forecast to fall 1.8% this year. Retail diesel margins doubled during the price spike and will fall back when it ends. Federal policy that would have forced electric trucks onto the road has been repealed, the driver pool is being tightened by regulation rather than demographics, and driverless trucks are running on ten Texas and Southwest lanes. Every one of those facts changes what a lender should credit in a pro forma, and this report takes them in order.
Where the freight cycle stands
The 42-month decline in the Cass Freight Index shipments series, the longest on record, ended in August 2026. Shipments rose 2.1% year over year that month and 1.9% in September, the first annual gains since January 2023 (2). On rates the turn came earlier and harder. The Cass Truckload Linehaul Index, which excludes fuel, reached 154.8 in September, up 10.1% year over year and the highest reading in four years, after falling 10% in 2023 and 3.4% in 2024 (2). DAT's September spot averages were $3.01 a mile for dry van, a record $3.62 for reefer and $3.61 for flatbed, and its estimated fuel surcharge set records for all three equipment types (3).
Volume has not followed. The American Trucking Associations' tonnage index fell in four of the five months through August and stood 1.6% below a year earlier, 4.3% below its March peak (4). ATA's chief economist put it plainly: "The truck market has certainly flipped this year, but recent tonnage levels confirm this is due to reduced capacity, not robust demand" (4). DAT's truckload volume index was down 1% for van and 10% for reefer in September (3). The recovery is a capacity story. Thousands of small carriers exited in 2023 to 2025, insurance costs rose 23.9% from 2021 to 2025 to 10.6 cents a mile (5), and the fleets that remain are pricing scarcity.
For a travel center that distinction matters more than the headline. Higher contract rates keep the diesel customer solvent and able to pay for a reserved parking space. They do not add gallons. FTR's Avery Vise warned in July that if record diesel forces out more small carriers, their drivers moving to large fleets "could relieve some of the tightness in trucking capacity" (6). Large fleets buy fuel on negotiated contracts at the chains. Owner-operators buy at the independent. A capacity-driven recovery that consolidates the customer base into big fleets is good for Pilot and Love's and neutral to negative for the independent interchange.
Class 8 orders tell the same story from the equipment side. September net orders were 21,300 units by FTR's count, with year-to-date orders up 95% on a pre-buy ahead of the EPA 2027 NOx engine rules, while ACT Research counted 18,700, down 9.5% year over year with the backlog expected to shrink (7). The pre-buy is over. Neither firm is forecasting fleet growth.
Diesel: record price, falling volume
The national average retail diesel price rose from $3.52 in January 2026 to $6.29 in September, a record, after the closure of the Strait of Hormuz cut oil flows through the strait from 21.6 million barrels a day in the fourth quarter of 2025 to 4.9 million in the second quarter of 2026 (8, 9). West Coast diesel averaged $7.26 in September and California $8.06 (8). The Energy Information Administration's October outlook puts the 2026 average at $5.19 and 2027 at $4.49, with prices above $6 through October and above $4 through the end of 2027 (9). The agency has raised its 2026 diesel forecast five times since November 2025, from $3.50 to $5.19, and its April assumption that the conflict would end that month failed (9). The current forecast is a base case, not a ceiling.
Volume is moving the other way. Distillate consumption, the best available proxy since EIA suspended its on-highway diesel sales series after 2020, peaked at 4.03 million barrels a day in 2022 and is forecast at 3.84 million in 2026, down 1.8%, before recovering to 3.89 million in 2027 (9, 10). The quarterly path lines up with the price spike: 4.04 million barrels a day in the first quarter, 3.72 million in the third.
The structural trend underneath the cycle is efficiency. Federal Highway Administration data put the combination-truck fleet at 6.0 miles per gallon in 2019 and 7.1 in 2024, a 15% reduction in gallons per mile in five years (11). Leading fleets in the North American Council for Freight Efficiency's annual study averaged 7.77 mpg in 2023, and two of four diesel trucks in its 2025 demonstration ran at 11.5 mpg (12). Combination-truck vehicle miles traveled fell 1.7% in 2024 to 192.5 billion, with interstates carrying 57% of those miles, and FHWA's baseline forecast has truck VMT growing 1.3% a year to 2040 (11, 13).
Put the two together and the five-year gallon outlook for heavy trucks is flat. MMCG's estimate, built from FHWA's VMT baseline and a 1% to 2% annual efficiency gain, is a cumulative change in heavy-truck diesel demand of somewhere between +2% and -3% over 2026 to 2031. That is not a sourced forecast; it is arithmetic on two public series, and we present it as such. The implication for underwriting is direct: a new travel center's gallons come from market share and location, not from industry growth. A projection that grows diesel volume at 3% a year on a stable site is projecting share gain, and the study should say where the share comes from.
What the price spike did to the operators is documented in their filings, and it is the same pattern in 2022 and 2026. Margins rise, gallons do not. TA's fuel gross margin went from $0.172 a gallon in the second quarter of 2021 to $0.273 in the second quarter of 2022 while diesel gallons were flat, and its full-year fuel gross margin rose 45.1% "partially offset by a slight decrease in fuel sales volume" (14). The company described the mechanism in its own words: "during periods of rising fuel commodity prices, fuel gross margin per gallon tends to be higher than it otherwise may have been and during periods of falling fuel commodity prices, fuel gross margin per gallon tends to be lower" (14). In the second quarter of 2026 Murphy USA earned 35.1 cents a gallon against 29.2 a year earlier on same-store gallons up 0.5%; Casey's earned 47.8 cents against 41.0 in its May to July quarter, on same-store gallons down 0.3%; Arko earned 48.7 cents with same-store gallons down 5.7%; CrossAmerica earned 49.2 cents, up 33%, with same-store volume down 11% (15, 16, 17, 18). CrossAmerica's management said margins "have already begun to moderate in the third quarter" (18). Pilot, inside Berkshire Hathaway, showed the other side of volatility: hedging losses pushed it to a pre-tax loss in the first quarter of 2026 before margins recovered in the second (19).
The lender's rule follows from the record. Underwrite diesel margin at a through-cycle figure, not at 2026. TA's 2021 trough was 17.2 cents (20). Casey's management cited OPIS data showing fuel gallons in its Mid-Continent region down about 6% this quarter and 10% over two years (16). A stress case at 16 cents a gallon after fleet discounts, on flat gallons, is the right floor for an independent interstate site.
Industry structure: three chains and a long tail
The industry is an oligopoly with a long independent tail. Pilot operates 675 travel centers and 82 fuel-only sites; Love's has about 670 locations in 42 states; bp's TravelCenters of America had about 280 sites when it was acquired in May 2023 (19, 21, 22). The National Association of Truck Stop Operators says it represents about 5,000 travel centers and truck stops, and TA's last annual report estimated about 6,500 in total (23, 1). No published source gives the independent share. Getty Realty's management told investors the top three operators own about 30% of roughly 5,000 travel centers (24). Berkshire describes the industry as "concentrated among a few large operators" with "numerous independent operators that operate one to ten travel centers" (19).
The chains hold far more than 30% of fleet diesel. Pilot alone sold about 10.9 billion gallons in 2025, down from 11.4 billion in 2024, including wholesale (19). Love's and Pilot together are the price on every corridor they occupy, and TA's own filings show why: 90.6% of its diesel was sold at discounts to posted prices under fleet pricing agreements, and diesel was 90.2% of fuel revenue (1). The posted price at the independent across the interchange is not its realized price either. Fleet and fintech fuel cards now advertise discounts of 10 to 45 cents a gallon at participating truck stops, and NATSO's vice president of membership has said the resulting price transparency is "putting a lot of pressure on the independents," adding that an operator "may realize you made less money at the end of the month and didn't sell enough additional gallons to offset what you traded away" (25).
Consolidation has been steady rather than dramatic. Berkshire took control of Pilot in January 2023 and bought the remaining 20% in January 2024 for total consideration of about $13.6 billion across three tranches (19, 26). bp paid $1.3 billion for TA, about six times trailing EBITDA, and said about 70% of TA's gross margin came from convenience rather than fuel (22). Maverik absorbed Kum & Go's roughly 400 stores in 2023 and finished the rebrand in November 2025; Casey's added 198 Fikes and CEFCO stores and opened 80 in its fiscal 2026 (27, 28).
The chains are moving in different directions, and that matters for anyone deciding where to build. Love's is the steady builder: 18 openings in 2025 and a $700 million 2026 plan for 20 new stores, 35 remodels, 1,500 new truck parking spaces and more than 52,000 spaces in total by year-end (29). Pilot under Berkshire is being run for cash and debt reduction, with revenue down 10% in 2025, pre-tax earnings down 69%, no unit growth target disclosed, and management focused on execution (19). bp's new chief executive named TA as a candidate for "targeted performance programmes" alongside a portfolio review that has already sold other assets; TA is a cost-out story, not a growth story (30). Buc-ee's opened four stores in 2026 and announced six for 2027, each 18 to 24 months to build, but Buc-ee's does not serve heavy trucks and competes for motorist gallons and inside sales, not diesel (31).
For an independent, the practical test is spacing. Love's describes its targets as corridors "underserved by our current locations" (29). A site 40 miles from the nearest chain node in each direction is a different credit from one at the next exit.
What one site earns
The best primary benchmark for a full-size interstate travel center is TA's fiscal 2022, the last full year it reported as a public company, and it should be read with the caveat that 2022 was a high-margin year. Across 239 company-operated sites, TA sold 2.28 billion gallons, about 26,000 gallons per site per day, with diesel 89% of the total (1). Fuel gross margin was about 25 cents a gallon for the year and 29.8 cents in the fourth quarter (1, 14). Non-fuel revenue was $2.12 billion: truck service $830 million (39%), store and retail services $775 million (37%), restaurants $332 million (16%) and diesel exhaust fluid $187 million (9%), at a blended 60.4% gross margin (1). Site-level operating expense consumed 57% of total gross margin, corporate overhead another 10%, and adjusted EBITDA of $366 million was 3.4% of revenue and about 20% of gross margin (32). EBITDAR, the right test for an owner-operator who does not pay a REIT $244 million a year in rent, was $626 million (32).
Three things in that statement should anchor every pro forma. First, truck service was TA's largest non-fuel line; a site without bays leaves the biggest margin pool on the table. Second, the 60.4% non-fuel margin against a 25-cent fuel margin is why fuel at 80% of revenue produces 31% of gross profit. Third, most of TA's 2022 earnings improvement came from fuel margin, which rose 45%; a normalization of fuel margin hits EBITDA almost dollar for dollar.
Below the chain tier the primary record thins out quickly, and a feasibility study should say so. The convenience industry as a whole earned fuel margins above 40 cents a gallon in 2025, with fuel at 65.0% of sales dollars but 38.8% of gross profit, and in-store sales of $341 billion (33, 34). Those are gasoline-weighted c-store figures, not diesel-weighted travel center figures. Seller-reported listings and model studies put an independent interstate truck stop at 7,000 to 9,300 diesel gallons a day, diesel margins of 16 to 25 cents, and inside sales of $50,000 to $130,000 a month; one Pilot-branded site near St. Louis reported 3.4 million gallons a year, 2.6 million of it diesel, and $2.5 million of inside sales including a $1.2 million restaurant (35). None of that is verified, and no operator publishes revenue for showers, scales, laundry or parking.
The one amenity with a primary per-site figure is video gaming, and it is confined to Illinois. The state's Commission on Government Forecasting and Accountability reports that the 100 locations running ten terminals in fiscal 2025, which only licensed large truck stops may do, averaged $1,313,230 of net terminal income, about $4,278 a day (36). At the 35% state tax and the statutory 50/50 split with the terminal operator, the host keeps about $427,000 a year (36, 37). A large truck stop must sell at least 50,000 gallons of diesel a month to qualify (37). The top site in the state produced $3.59 million in 2024; that is not a norm (38). An Illinois travel center with gaming is a different asset from one without it, and the state's rules, not the operator's projection, set the ceiling.
Costs have one primary anchor and several project records. NATSO's new-build guidance states that a full travel center "can easily exceed $20 million all in" on ten or more acres, and that a new build takes about two years (39). TA's franchising materials say a new TA or Petro "can cost as much as $26.5 million," on 20 acres with 125 paved truck spaces, a building of at least 14,000 square feet, six diesel lanes with DEF, a three-bay shop, six showers, laundry and a scale; a TA Express needs 8 to 10 acres and 50 truck spaces (40). The franchised TA under construction at Laurel, Mississippi on I-59 is budgeted at $15 million to $20 million (41). A Love's at a New York Thruway exit on 7.23 acres with 37 truck spaces was estimated at about $20 million before water and sewer extensions (42). Wally's 54,000-square-foot plaza in Independence, Missouri is carried at $52 million to $53 million in city records, including about $10 million of off-site traffic work, against $40 million in company statements; the city figure is the one to use (43). At the other end, a 24-hour travel center conversion in Webster City, Iowa was budgeted at $4.6 million of improvements excluding land, and a 12,895-square-foot new build in Pilot Point, Texas at $10.0 million (44, 45).
Two cost lines deserve a lender's attention because budgets routinely understate them. Truck-grade paving at $7 to $15 a square foot, on 2,000 to 2,500 square feet per space including aisles, works out to roughly $16,000 to $37,500 per truck space before lighting and drainage; a 100-space court is $1.6 million to $3.8 million of concrete (46). Off-site road and utility work added $2 million to $10 million in the New Baltimore and Independence records (42, 43). For comparison, the median state cost of a public truck parking space in ATRI's 2025 study was $93,500, and Florida's 160-space I-4 facility is costing $29.4 million, about $184,000 a space with ramp work (47, 48). Public projects carry costs a private court does not, but they show what the land, pavement and access actually cost when nobody is rounding down.
Parking: the shortage that became a product
The federal inventory counts about 313,000 truck parking spaces nationally, 40,000 at public rest areas and 273,000 at private truck stops, from survey data collected in 2018 and 2019 (49). No newer federal count exists. ATRI and AASHTO's 2025 study puts the ratio at one truck parking space for every eleven truck drivers (47). Of roughly 11,700 drivers surveyed for the federal study, 98% reported problems finding safe parking, and the most-cited diary study found drivers spending 56 minutes a day looking for it, at a cost of about 9,300 revenue miles and $4,600 in wages a year (49, 50). The ATA's version, citing USDOT, puts the cost at about $5,500 a year, a 12% pay cut (51). Truck parking has appeared on ATRI's annual list of the industry's top concerns for ten years (52).
What has changed since the 2019 survey is that operators have started charging for it. In 2019, 79% of truck stop operators said they had no plans to add parking, 73% did not monitor occupancy and 78% did not offer reservations (49). Pilot's Prime Parking now runs at more than 390 locations; on its location pages checked in October 2026, reserved spaces are roughly 15% to 30% of the lot, and one New Jersey site lists $18 a night (53). TA runs gated parking at 12 U.S. sites with a $25 fee waived for a $30 purchase, and 60 gallons of fuel buys up to 24 hours free; TA has said paid parking is capped at half of a site's capacity (54, 55). Truck Parking Club, a marketplace that lets any property owner rent spaces, grew from 4,000 locations in February 2026 to more than 6,000 by August, with 92 of the top 100 carriers using it (56, 57). Love's, by contrast, is adding 1,500 free spaces in 2026 and describes parking as "free parking for Love's customers" (29).
No operator discloses parking revenue or utilization. That is the single most important gap for anyone underwriting a travel center on its parking count. The arithmetic is suggestive: 50 reserved spaces at $18 a night is $328,500 a year at full occupancy, and occupancy is unknown. A lender should treat reserved parking as upside and ask the borrower for reservation-system reports, not pro forma assumptions. The Truck Parking Safety Improvement Act, which would fund public spaces that by statute could not charge a fee, has sat in a House subcommittee since February 2025 with a 20% enactment probability (58). Even if it passes, grant-funded free public spaces would compete with paid private ones on the corridors they target.
The hours-of-service rules fix the timing of the demand. An 11-hour driving limit inside a 14-hour window, enforced by electronic logging devices, means demand piles up between 4 p.m. and 7 p.m. at sites roughly one driving day from freight origins; 63% of parking searches longer than 15 minutes happen in that window (59). Two FMCSA pilot programs that would loosen the sleeper-berth split and let drivers pause the 14-hour clock were proposed in September 2025 and are now expected to run in 2027 (60). Nothing on the 2026 agenda changes overnight parking demand through at least 2027.
Drivers and regulation
The driver pool is being tightened by rule rather than by demographics, and the two rules in play reach the long-haul drivers who use travel centers most.
The Federal Motor Carrier Safety Administration's final rule restricting non-domiciled commercial driver's licenses took effect March 16, 2026, limiting eligibility to holders of H-2A, H-2B and E-2 visas and capping license terms at one year (61). The agency's own estimate is that about 194,000 current non-domiciled CDL holders will lose eligibility to renew as their licenses expire over the next five years, against roughly 200,000 such holders in total (61). A D.C. Circuit panel denied a stay 2-1 in May, heard the merits on September 15, and had not ruled as of mid-October (62). In parallel, English-language-proficiency enforcement was restored to the out-of-service criteria in June 2025, Congress directed FMCSA to codify it in February 2026, and the agency's administrator said in August that it had "already pulled over 26,000 unqualified drivers off the road" (63, 64).
The scale is modest against a Bureau of Labor Statistics count of about 2.1 million heavy and tractor-trailer drivers, roughly 9% if the full 194,000 leave, and it phases in over years (65). Truck transportation payroll employment posted its first year-over-year gain in more than three years in September 2026, at 1,473,100, still below the October 2022 record (66). ATA stopped publishing a numeric driver shortage estimate after "60,000 or less" in October 2023 and now describes a shortage of "quality, not quantity" (67). For a travel center the effect is a mild drag on gallons and overnight stays on the corridors where affected drivers are concentrated, chiefly long-haul lanes in California and Texas, and a mild support to freight rates. It does not close a one-to-eleven parking gap.
The regulatory risk a construction lender should price is local, not federal. Greenfield travel centers now draw organized opposition in a way they did not a decade ago. A county board in Virginia voted down a Love's in September 2024 on water, sewer and traffic grounds; a Love's near Moab has been contested for nearly six years; residents in St. Clair, Missouri asked for a ten-foot sound wall; a Texas applicant withdrew after a neighbor objected to all-night lighting a hundred yards from homes; an Indiana planning commission recommended denial of a $17 million Love's on light, noise, idling and groundwater (68, 69, 70, 71, 72). The conditions that get a project through are now standard: earthen berms and vegetated buffers, 100- to 200-foot setbacks, shielded downcast lighting, sound walls, traffic signals or turn lanes, stormwater ponds and electrified parking to cut idling. A construction loan should fund after rezoning is final and appeal periods have run, with the conditions of approval in the budget.
The energy transition, written soberly
A travel center financed in 2026 on a 25-year amortization will be a diesel-and-amenities business for most of that term, and quite possibly all of it. The evidence for that statement is not a forecast but a count.
Class 8 battery-electric tractor registrations fell 24% in 2025 to 671 units, in a Class 8 market measured in the hundreds of thousands (73). Of the zero-emission heavy trucks registered in the third quarter of 2025, the leading manufacturer made yard tractors that never leave a terminal (74). Nikola is bankrupt, Traton cancelled its International Class 8 battery-electric tractor, and Daimler Truck North America cut its workforce 10% (73, 74). Tesla's Semi entered volume production in Nevada in 2026 at a plant sized for 50,000 trucks a year, with no published timetable to reach that figure and an order book, not a delivery record, of a few thousand units (75). The median price of a model year 2024 battery-electric heavy tractor in the United States was $379,800 (76).
The policy that would have forced the pace is gone, for now. EPA repealed all vehicle greenhouse gas standards, including the Phase 3 heavy-duty rule for model years 2027 to 2032, effective April 20, 2026 (77). Congress used the Congressional Review Act in June 2025 to void the waivers behind California's Advanced Clean Trucks rule, California withdrew its Advanced Clean Fleets waiver request and repealed the private-fleet provisions effective September 10, 2026, and the litigation over all of it is pending (78, 79). The 2027 NOx engine rule survives and is what is driving truck orders (7). A lender should model a scenario in which zero-emission requirements return in the 2030s rather than assume permanent repeal; the pendulum has swung twice in five years.
Charging is the capital question, and the answer is that a borrower should not fund it. A truck charging depot costs $7.9 million to $15.4 million by the ICCT and Black & Veatch estimate, roughly the cost of the travel center itself, with grid connection waits measured in years (80, 81). Pilot opened its first Tesla Megacharger site on October 8, 2026 in Ellabell, Georgia, with six 1.2-megawatt stalls, Tesla-only at launch, later than promised, with twelve more under construction (82). Greenlane's Colton, California hub opened in April 2025 with 41 charging points and a $15 million state grant (83). Federal money is going the other way: Congress redirected about $879 million of unobligated NEVI funds in February 2026, the administration has proposed cancelling $4.2 billion more, and the discretionary charging grant program was paused with funds lapsing (84). The right structure for a 2026 build is a charging-ready site plan, with pull-through space, a utility easement and conduit, and a ground lease to an operator that carries the capex. Charging revenue should be excluded from debt service coverage. The same applies to light-vehicle charging: EVgo's network averages 276 kilowatt-hours per stall per day, about $62,600 of revenue a stall at 20% utilization, and rural utilization runs in low single digits (85, 86).
The transition that will actually show up at a travel center is inside the tank. EIA forecasts renewable diesel production of 230,000 barrels a day in 2026 and 290,000 in 2027, up from 190,000 in 2025; it uses the same tanks and dispensers (87). Renewable natural gas has an operating long-haul engine in the Cummins X15N and a national network of more than 600 Clean Energy stations, but at 237 million gallons a year it is a niche developed by specialists on pad leases, not by independent owners (88). Hydrogen retail has contracted, and fuel cell truck registrations fell 12% in 2025 (73).
The transition risk most likely to bite inside the loan term is not electrification. It is the driverless truck, and it is lane-specific. Aurora runs driverless operations on ten routes across Texas and the Southwest, including a nonstop 1,000-mile Fort Worth to Phoenix lane that takes about 15 hours, longer than a human may legally drive in a day; it had logged nearly 440,000 driverless miles through June 2026 with no Aurora-attributed collisions and guided to 200 driverless trucks by year-end, with 20 to 25 in operation by the end of the third quarter (89, 90). Kodiak's system runs 35 driverless trucks for Atlas Energy Solutions in the Permian Basin, and Kodiak targets driverless Dallas to Houston service by the end of 2026 (91). These operations are hub to hub. A driverless truck fuels and inspects at a terminal, needs no shower, no meal and no ten-hour parking space, and removes the highest-margin, driver-dependent spend from any travel center on its lane. A site on I-45, I-20, I-10 or I-35 toward Laredo should be stress-tested for a 15% to 30% reduction in non-fuel gross profit in the second decade of the loan. Sites that also serve local, four-wheeler and regional traffic carry the hedge.
How the loans are financed and how they perform
SBA data has no truck stop code. Truck stops sit inside the gasoline station codes, 447110 and 447190 under the 2017 classification and 457110 and 457120 under the 2022 revision, so any portfolio statistic for the asset class inherits the gas station mix, which is dominated by single-site convenience stores. MMCG's analysis of the SBA 7(a) and 504 loan-level data as of March 31, 2026 separates the two as far as the record allows, and the result is the most specific public view of how this asset class performs (92).
Across the four fuel retail codes, SBA approved 9,246 7(a) loans for $11.1 billion and 1,704 504 loans for $1.5 billion from fiscal 2010 through the first half of fiscal 2026, excluding cancellations (92). Borrowers whose names identify them as truck stops, travel centers, travel plazas or fuel stops account for 121 of those loans, $219 million in all: 85 7(a) loans averaging $1.88 million and 36 504 loans averaging $1.64 million (92). That is the honest finding. SBA finances a great many gas stations and very few named travel centers, because a full interstate travel center costs more than the $5 million 7(a) ceiling, and the ones it does finance have gotten larger: the average named truck stop 7(a) loan rose from $1.64 million in the fiscal 2010 to 2019 cohort to $2.30 million in fiscal 2021 to 2026, and the average 504 debenture from $729,000 to $2.64 million (92). Startups were 30% of recent 7(a) truck stop approvals, against 6% in the seasoned cohort (92).
Performance is where the asset class earns its reputation. On the seasoned fiscal 2010 to 2019 cohort, 7(a) loans across all fuel retail codes have charged off at 3.36% of loans and 0.99% of dollars, against 6.44% of loans and 2.93% of dollars for the entire 7(a) program (92). The 504 fuel book charged off 2.02% of loans and 1.32% of dollars, somewhat above the 0.99% dollar rate for the 504 program as a whole (92). The named truck stop subset is too small to carry a rate of its own, 47 seasoned 7(a) loans with three charge-offs, but its dollar loss rate of 0.98% matches the broader fuel book. The travel center's core customer is a far weaker credit: seasoned 7(a) loans to long-haul truckload carriers charged off at 7.71% of loans and 4.28% of dollars (92).
The structural pattern inside the fuel book is the one a lender can act on. Charge-off rates fall steadily with loan size: 6.68% of loans and 3.55% of dollars for fuel loans of $350,000 or less, 2.84% and 1.41% for $350,000 to $1 million, 1.71% and 0.80% for $1 million to $2 million, and 1.16% and 0.55% for $2 million to $5 million (92). Small, lightly secured loans to a capital-intensive business are structurally weak; large real-estate-secured loans are not. The 504 structure adds a second layer of protection: the bank's first lien sits ahead of SBA's debenture, and the borrower's 10% to 20% equity sits ahead of both. The extra 5% equity SBA requires for special purpose property is cheap protection on an asset whose collateral value depends on the operator.
The rulebook tightened on October 1, 2026 without changing the travel center specifics. SOP 50 10 8.1 lists "gas stations with or without convenience stores" among special purpose properties, which drives the 504 equity contribution to 15% for special purpose property or a new business and 20% where both apply, and requires an appraisal from a certified general appraiser with at least four going-concern appraisals of equivalent special use property in the prior 36 months, allocating value among land, building, equipment and intangibles (93). Gas stations are the one asset class for which SBA requires a Phase I environmental site assessment regardless of loan amount, and any party holding a right of environmental indemnification must waive it through SBA's agreement; if that waiver cannot be obtained, the loan is ineligible (94). The new SOP adds a 1.25x historical debt service coverage test on business acquisitions, a 10% minimum equity injection, and a lender-ordered quality of earnings review at $3 million or more (93). It imposes no blanket feasibility study requirement; SBA may request one on 504 projects for market saturation, a unique concept, a highly specialized property, or a project out of scale with its community, and lender credit policy requires one for most startups and new construction in this asset class (93).
USDA is where the larger rural travel centers get built, because a $15 million to $27 million project cannot fit inside SBA's limits. The Business and Industry guaranteed loan program reaches $25 million per borrower for projects outside towns of 50,000 and their urbanized areas, and 7 CFR 5001.306 provides that "for guaranteed loans greater than $1,000,000.00 to a new business, a feasibility study prepared by an independent qualified consultant acceptable to the Agency is required" (95). A new business includes an existing operator opening in a new market. The study must follow Appendix A to Subpart D, with executive summary, economic, market, technical, financial, management, recommendation and qualifications sections, a sensitivity analysis in the financial section, and the lender must file its own written evaluation of it (95). USDA has funded the format: a $9.7 million B&I guarantee for a new gas and diesel fuel stop with commercial truck diesel pumps, a convenience store and a restaurant appears in the agency's own project chart (96). A travel center with video gaming must also clear the program's 15% cap on gross revenue from gambling (97).
Conventional capital prices operator risk, and the spread is wide. A Pilot ground lease in Jurupa Valley, California closed at a 4.90% capitalization rate in March 2024, a record for the brand outside Texas (98). Getty Realty made its first travel center investments in 2025, four assets for $47.1 million at yields consistent with its 7.9% portfolio average, and told investors the segment could reach 5% to 10% of its book (24). Franchisee-guaranteed TA and independent travel center sale-leasebacks were being offered in late 2025 and 2026 at 7.5% to 8.25%, including a Columbia, South Carolina TA at $28.4 million and 7.75% on a 30-year absolute net lease (99). Service Properties Trust's 175 TA sites carry $259 million of annual minimum rent, guaranteed by bp, at 1.34x coverage (100). Going-concern businesses trade on a different basis altogether: truck stops reported sold from 2021 to 2025 had a median price of $5.25 million at 0.71 times revenue and 3.69 times owner earnings, on self-reported broker data skewed to small independents (101). An appraisal that applies a chain-credit cap rate to an independent's real estate overstates the collateral; the spread between 4.9% and 7.75% is the market's price for the operator.
No truck stop operator has filed for bankruptcy protection since Flying J in 2008, which ended with Pilot's acquisition of about 250 travel plazas and an FTC-ordered sale of 26 sites to Love's (102). The distress sits in the customer base. Freight carriers filed 20 bankruptcy petitions in the second quarter of 2025 and 21 in the third, and small Subchapter V filings followed the September 2026 diesel record (103). The OCC's commercial real estate handbook names gas stations among property types with elevated environmental liability and warns that contaminated collateral can be "worthless"; examiners expect an environmental risk program with professional assessments before commitment and monitoring for the life of the loan (104).
What a feasibility study should show
Everything above reduces to a short list of things a lender-grade study must contain for this asset class, and the order matters.
Corridor and spacing. The traffic count is context, not a demand model; no published ratio converts annual average daily traffic to gallons. What the study must show is the distance to the nearest Pilot, Love's and TA node in each direction, every planned interchange, bypass and closure within the loan term, and the share of corridor traffic that is long-haul versus regional and four-wheeler. A site that depends on a forced detour, as Breezewood, Pennsylvania's plazas do, carries a risk no portfolio statistic captures (105).
Diesel at realized margin. Gallons built up from truck counts and capture, not from a growth rate; margin stated after fleet and fintech discounts and card fees, from fuel management data where an existing site is being acquired; a stress case at 16 cents or less on flat gallons.
Non-fuel gross margin by line. Store, restaurant or franchised QSR, truck service, showers, scales, laundry, parking and gaming shown separately with their own margins, because that is where two-thirds of the gross profit sits and where the lender's coverage actually comes from. Gaming at the state's published average with a haircut for secondary interchanges, never at the top site.
A line-item budget with off-site costs shown separately. Truck-court paving at no less than $16,000 a space; road and utility extensions as their own line; conditions of approval priced in; land at a verified interchange comparable rather than a per-acre average from a 200-acre tract.
Ramp and coverage. A build to stabilized volume over two to three years, debt service coverage above 1.25x in the base case, and the three stress cases this report has described: fuel margin normalization, flat gallons, and, for Sunbelt lanes, a second-decade loss of 15% to 30% of non-fuel gross profit to driverless freight.
Program compliance. For SBA, the special purpose equity tier, the going-concern appraisal, the Phase I and the environmental indemnification waiver resolved before approval. For USDA, Appendix A followed section by section, the sensitivity analysis included, the gaming revenue test documented, and the study started at term sheet rather than at closing.
A travel center is a sound credit when it is financed as what it is: a real estate going concern whose fuel pays the overhead and whose building pays the debt. The 2026 record, from the diesel spike to the FOIA data, says the same thing from every direction. That is the analysis MMCG Invest delivers in every truck stop and travel center study prepared for SBA, USDA and conventional lenders.
Frequently asked questions
How much does it cost to build a truck stop or travel center in 2026?
Public project records put a full-service interstate travel center at $15 million to $27 million all-in: the franchised TA under construction in Laurel, Mississippi at $15 million to $20 million, a Love's at a New York Thruway exit at about $20 million before utility extensions, and TA's own ceiling of $26.5 million for a new TA or Petro on 20 acres with 125 truck spaces (40, 41, 42). A convenience store with a few diesel lanes runs about $4.6 million to $10 million (44, 45).
How much diesel does a travel center sell?
TA's company-operated sites averaged about 26,000 gallons a day in 2022, with diesel 89% of the total (1). Seller listings and model studies for independent interstate truck stops show 7,000 to 9,300 diesel gallons a day, unverified (35). Industry diesel demand is forecast to fall 1.8% in 2026, and heavy-truck gallons are flat over five years once fleet efficiency gains offset mileage growth (9, 11).
What fuel margin should a lender underwrite on a truck stop?
A through-cycle figure, not a 2026 figure. TA earned 17.2 cents a gallon in its 2021 trough and about 25 cents across the 2022 spike; chain retailers earned 35 to 49 cents in the second quarter of 2026 while gallons fell (14, 15, 16, 17, 18, 20). An independent site should be stressed at 16 cents or less after fleet discounts of 10 to 45 cents a gallon (25).
Does SBA require a feasibility study for a truck stop loan?
Not automatically. SOP 50 10 8.1 lets SBA request one on 504 projects for market saturation, a unique concept, a highly specialized property, or a project out of scale with its community; lender credit policy requires one for most startups and new construction (93). Gas stations and truck stops are special purpose property, which raises the 504 equity tier and requires a going-concern appraisal and a Phase I regardless of loan size (93, 94).
Does USDA require a feasibility study for a travel center?
Yes, for Business and Industry guaranteed loans above $1,000,000 to a new business, which includes an existing operator entering a new market. The study must follow Appendix A to Subpart D of 7 CFR Part 5001, and the lender must file a written evaluation (95).
How do SBA loans on gas stations and truck stops perform?
Better than the program. On the seasoned fiscal 2010 to 2019 cohort, 7(a) loans to fuel retailers charged off at 3.36% of loans and 0.99% of dollars, against 6.44% and 2.93% for all 7(a) loans. Losses fall with size: 6.68% of loans under $350,000 against 1.16% between $2 million and $5 million. Named truck stops are a small subset, 121 loans since 2010, with a dollar loss rate in line with the fuel book (92).
Will electric trucks make a travel center obsolete before the loan is repaid?
Not on the evidence. Class 8 battery-electric registrations were 671 units in 2025, the federal and California rules that would have forced adoption were repealed in 2025 and 2026, and a truck charging depot costs as much as the travel center itself (73, 77, 80). The transition inside the loan term is renewable diesel in the same tanks. The risk to watch is driverless freight on Texas and Southwest lanes, which removes driver spend without removing the truck (89).
Is paid truck parking a bankable revenue line?
Not yet. The shortage is real, about one space for every eleven drivers, and Pilot and TA now charge for reserved spaces, but no operator discloses parking revenue or occupancy, and Love's gives parking away free (47, 53, 54, 29). Underwrite it as upside and ask for reservation-system reports.
Sources
- TravelCenters of America Inc., Form 10-K for fiscal year 2022, filed March 1, 2023
- Cass Information Systems, Cass Freight Index and Cass Truckload Linehaul Index reports, August and September 2026
- DAT Freight and Analytics, truckload rate and volume release for September 2026, October 13, 2026
- American Trucking Associations, For-Hire Truck Tonnage Index, August 2026
- American Transportation Research Institute, An Analysis of the Operational Costs of Trucking, 2026 update, July 15, 2026
- FTR Transportation Intelligence, Trucking Conditions Index commentary, July and August 2026
- FTR and ACT Research, preliminary North American Class 8 net orders, September 2026
- U.S. Energy Information Administration, Weekly Petroleum Status Report, Table 14, retail on-highway diesel prices, January to September 2026
- U.S. Energy Information Administration, Short-Term Energy Outlook, October 6, 2026, and prior editions November 2025 to September 2026
- U.S. Energy Information Administration, distillate fuel oil product supplied, annual, and sales of distillate fuel oil by end use
- Federal Highway Administration, Highway Statistics, Table VM-1, 2019, 2020, 2023 and 2024
- North American Council for Freight Efficiency, Annual Fleet Fuel Study and Run on Less demonstration, 2023 to 2025
- Federal Highway Administration, Spring 2024 VMT Forecast
- TravelCenters of America Inc., quarterly earnings releases, Q1 2022 to Q1 2023, and Form 10-K for fiscal year 2022
- Murphy USA Inc., second quarter 2026 results, August 5, 2026
- Casey's General Stores, first quarter fiscal 2027 results and earnings call, September 2026
- Arko Corp., second quarter 2026 results and earnings call, August 2026
- CrossAmerica Partners LP, second quarter 2026 results, August 2026
- Berkshire Hathaway Inc., 2024 and 2025 Annual Reports, shareholder letters, and Forms 10-Q for 2025 and 2026
- FreightWaves, TravelCenters of America second quarter 2021 earnings coverage
- CSP Daily News, Top 202 Convenience Stores 2026, and Love's store opening coverage, February 2026
- bp p.l.c., press releases on the acquisition of TravelCenters of America, February and May 2023
- NACS, NATSO and SIGMA, comment letter to the Environmental Protection Agency, August 8, 2025
- Getty Realty Corp., FY2025 annual report, 2025 business update, January 8, 2026, and Q3 and Q4 2025 earnings calls
- NATSO, Fintech Companies Offer Options for Drivers and Truckstop and Travel Plaza Operators; DAT, fuel card discount survey; AtoB, Mudflap and Comdata program disclosures
- MMCG Invest, Pilot Flying J vs. Love's Travel Stops: Inside the Economics of America's Travel Center Duopoly, July 2026
- CSP Daily News, Maverik rebrands last Kum & Go convenience stores, November 26, 2025
- Casey's General Stores, fiscal 2026 fourth quarter and full year results
- Love's Travel Stops, 2026 Road Ahead Plan announcement, February 5, 2026, and June and August 2026 expansion releases
- bp p.l.c., second quarter 2026 results commentary; C-Store Dive, TravelCenters of America under scrutiny as bp continues portfolio review, August 2026
- Yahoo News and Nexstar, Buc-ee's 2026 openings and 2027 announcements, September 22, 2026
- TravelCenters of America Inc., fourth quarter and full year 2022 financial results, February 28, 2023
- NACS, U.S. Convenience In-Store Sales Top $340 Billion, State of the Industry release, April 15, 2026
- NACS Magazine, 5 Key Metrics Defining the Convenience Industry's Health, June 2026
- BizBuySell, BizQuest and broker listings for truck stops and travel centers, 2025 to 2026, seller-reported figures
- Illinois Commission on Government Forecasting and Accountability, Wagering in Illinois, 2025 Update
- Illinois Video Gaming Act, 230 ILCS 40; Illinois Gaming Board, licensed large truck stop establishment requirements
- Chicago Reader, citing Illinois Gaming Board 2024 location data
- NATSO Foundation, Key Phases for Planning a Truck Stop or Travel Center New Build
- TravelCenters of America, franchising requirements and frequently asked questions
- Laurel Leader-Call, TA Travel Stop breaks ground, citing the Jones County Economic Development Authority, 2026
- The Daily Gazette, Love's travel stop site plan, New Baltimore, New York, planning board coverage
- City of Independence, Missouri, TIF Commission and City Council records on the Wally's travel center, 2025 to 2026
- City of Webster City, Iowa, council staff report on the 407 Clauss Drive travel center TIF request
- Texas Department of Licensing and Regulation, project registration for T&J Travel Center, Pilot Point, Texas
- Michigan Concrete Association standard pricing via G&G Concrete; Forta Corporation, cost of fleet lots; WinsParking, parking lot construction cost; MMCG derivation per truck space
- American Transportation Research Institute and AASHTO, Expanding Truck Parking at Public Rest Areas, 2025
- Florida Department of Transportation, I-4 Truck Parking Facility, Plant City, project 448698-1-52-01
- Federal Highway Administration, Jason's Law Truck Parking Survey and Assessment, 2015 survey and 2019 update, National Coalition on Truck Parking meeting, December 1, 2020
- American Transportation Research Institute, truck parking driver diary study, 2016
- American Trucking Associations, statement on the Truck Parking Safety Improvement Act
- American Transportation Research Institute, Critical Issues in the Trucking Industry 2025, October 26, 2025
- Pilot Company, Prime Parking frequently asked questions and location pages, checked October 2026
- TravelCenters of America, gated parking fees and locations, checked October 2026
- Land Line Media, TA Reserve-It! parking cap, undated
- Truck Parking Club, 4,000 locations release, PR Newswire, February 4, 2026
- Transport Topics, Truck parking marketplace gains traction with fleets, August 4, 2026
- Congress.gov and GovTrack, H.R. 1659, Truck Parking Safety Improvement Act, 119th Congress
- American Transportation Research Institute, driver diary study, ELD and time-of-day findings, via Commercial Carrier Journal
- Federal Register, FMCSA Flexible Sleeper Berth and Split Duty Period pilot program notices, September 17, 2025; Trucking Info, pilot programs readied for 2027, August 27, 2026
- Federal Register, 91 FR 7044, Restoring Integrity to the Issuance of Non-Domiciled Commercial Drivers Licenses, February 13, 2026; Holland & Knight summary of FMCSA regulatory analysis
- D.C. Circuit, No. 26-1032, stay denial May 5, 2026 and oral argument September 15, 2026, via Land Line Media and Overdrive
- Federal Register, English Language Proficiency; Out of Service Criteria, proposed rule, August 10, 2026
- Federal Motor Carrier Safety Administration, press release, August 7, 2026
- U.S. Bureau of Labor Statistics, Occupational Employment and Wage Statistics, heavy and tractor-trailer truck drivers, May 2025
- U.S. Bureau of Labor Statistics, truck transportation payroll employment, September 2026, via FreightWaves
- American Trucking Associations, driver shortage statements, October 2023 and October 2025, via Trucking Dive and Commercial Carrier Journal
- WTVR, Louisa County, Virginia rejects Love's Travel Stop plan, September 3, 2024
- Moab Times, Love's Travel Stop decision in San Juan County, Utah, 2025
- CitizenPortal, St. Clair, Missouri Board of Aldermen meeting on proposed Love's, 2026
- CitizenPortal, Weatherford, Texas truck stop rezoning withdrawal, 2025
- Tristate Homepage and 14 News, Vanderburgh County, Indiana planning commission vote on proposed Love's, November 2023
- Truck News, 2025 registration data presented by TRC, 2026
- International Council on Clean Transportation, Race to Zero, zero-emission bus and truck market in the United States, July to September 2025, January 2026
- CNBC, Quartz and Electrek, Tesla Semi volume production and Nevada plant inauguration, September 24 and 25, 2026; Tesla, Inc., Form 8-K, Q4 2025 update
- International Council on Clean Transportation, battery electric commercial vehicle pricing working paper, September 2025, and Truck electrification at a crossroads, April 2026
- U.S. Environmental Protection Agency, Rescission of the Greenhouse Gas Endangerment Finding and Motor Vehicle Greenhouse Gas Emission Standards, final rule, published February 18, 2026, effective April 20, 2026
- Public Laws 119-15, 119-16 and 119-17, June 12, 2025; Alston & Bird, Advanced Clean Trucks litigation update, June 2026
- California Air Resources Board, Advanced Clean Fleets repeal of 13 CCR 2014 and 2015, effective September 10, 2026, via Commercial Carrier Journal and ACT News
- International Council on Clean Transportation and Black & Veatch, The cost of energizing medium- and heavy-duty truck charging facilities in the United States, October 2025
- RMI, Getting Electric Truck Chargers Online Faster, May 19, 2026
- Pilot Company, Pilot and Tesla Open First Megacharger Site, press release, October 8, 2026; FreightWaves, October 14, 2026
- electrive and Mortenson, Greenlane Colton charging hub opening, April 2025
- Congressional Research Service, R48996, Implementation of Electric Vehicle Charging Infrastructure Programs: CFI and NEVI, 2026
- EVgo Inc., second quarter 2026 results, August 5, 2026, and investor materials
- Paren, U.S. DC fast charging utilization reports, 2025
- U.S. Energy Information Administration, Short-Term Energy Outlook, renewable diesel and biodiesel forecasts, October 2026
- Clean Energy Fuels Corp., 2026 proxy statement, May 4, 2026 release and second quarter 2026 earnings call; Transport Topics on the Cummins X15N
- Aurora Innovation, Inc., Q2 2026 shareholder letter, Form 8-K, July 29, 2026, and Q2 2026 earnings call; Aurora driverless route announcements, 2025 and 2026
- TechCrunch and Overdrive, Aurora Fort Worth to Phoenix driverless lane, February 2026
- Kodiak AI, press releases, September 2026, and Atlas Energy Solutions driverless fleet disclosures
- MMCG Invest, analysis of U.S. Small Business Administration 7(a) and 504 FOIA loan-level data, FY2010 to FY2026, as of March 31, 2026; charge-off defined as charged-off status or any gross charge-off amount; truck stops identified by borrower name within NAICS 447110, 447190, 457110 and 457120
- U.S. Small Business Administration, SOP 50 10 8.1, Information Notices 5000-880695, August 14, 2026, and 5000-882227, September 25, 2026, effective October 1, 2026; NAGGL and PilieroMazza summaries
- Starfield & Smith, Best Practices: SBA Gas Station Loans, June 26, 2024; SBA environmental policy for NAICS 457 properties
- 7 CFR Part 5001, sections 5001.3 and 5001.306, and Appendix A to Subpart D, Electronic Code of Federal Regulations, current as of October 13, 2026
- USDA Rural Development, New and Better Markets project chart, May 24, 2022
- USDA Rural Development, Business and Industry Loan Program Frequently Asked Questions and program guarantee terms, FY2026
- RealSource Group, Pilot Flying J ground lease sale, Jurupa Valley, California, March 2024, via ConnectCRE
- Crexi and broker listings, TA Travel Center sale-leaseback offerings, Columbia, South Carolina and Ohio, October 2025 to 2026
- Service Properties Trust, Form 10-Q for the quarter ended March 31, 2025
- BizBuySell, truck stop valuation benchmarks, businesses sold 2021 to 2025
- Federal Trade Commission, press release on Pilot's acquisition of Flying J, June 30, 2010
- TheStreet and FreightWaves, trucking bankruptcy coverage, 2025 to 2026
- Office of the Comptroller of the Currency, Comptroller's Handbook, Commercial Real Estate Lending, Version 2.0
- TribLive, Breezewood interchange reconfiguration coverage; EBP, Economic Impact of Freeway Bypass Routes in Medium Size Cities
Michal Mohelsky, J.D., FMVA, Practicing Affiliate of the Appraisal Institute
Principal, MMCG Invest, LLC
Published October 15, 2026. How this analysis was prepared.
Cite this
Michal Mohelsky, J.D., FMVA (2026). U.S. Truck Stop and Travel Center Market Outlook 2026: Freight, Diesel, Parking and What Lenders Should Underwrite. MMCG Invest, LLC. https://www.mmcginvest.com/post/us-truck-stop-travel-center-market-outlook-2026
Where this goes next
- Truck Stop Feasibility StudyMMCG's feasibility study page for this subject.