Land is worth what can be built on it, so a parcel should be priced from the residual rather than from comparable sales, with the four tests run in order before the deposit hardens.
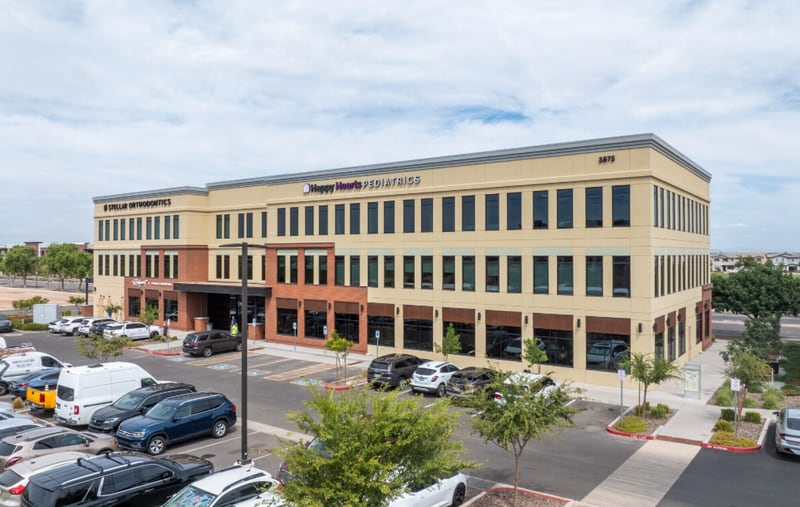
Medical outpatient buildings are a different asset from office and should be bought or held rather than built: national MOB vacancy was 9.8 percent in Q4 2025 against 18.6 to 21.0 percent for traditional office, asking rents set a record at $25.40 per square foot triple net, and delivering a new building costs $400 to $560 per square foot while existing buildings trade at $310 to $374.
The reserve conventions that lenders recite, $250 a unit for multifamily, $0.15 a square foot for retail, industrial and self-storage, $0.20 for office and 4 to 5 percent of revenue for hotels, are historical artifacts from HUD Mortgagee Letter 2010-21 and conduit prospectuses filed with the SEC in 2003 and 2004, and they understate what buildings actually consume.
The five national rental vacancy figures published for the first quarter of 2026, 4.8 percent from CBRE, 5.1 from RealPage, 5.7 from Yardi Matrix, 7.3 from the Census Bureau and roughly 8.5 from CoStar, are facts about methodologies rather than facts about the market, and the working rule is to match the source to the question and label the basis of every figure that enters a credit file.
Build-to-suit net lease development is decided by the development spread, stabilized yield-on-cost less the exit cap rate, and in 2026 that spread is thin enough that site-specific evidence, not the tenant's logo, settles the deal.
The boundary an analyst draws decides the feasibility conclusion, because every figure after delineation is a multiplication against the population that boundary enclosed.
Equity injection is three different questions under one name: the SBA states a floor, the USDA tests the borrower's balance sheet, and the conventional market names no floor at all, deriving the equity as the residual after sizing the largest loan the property's own cash flow can carry.
25 minute read
Show the remaining 54 studies in Valuation Fundamentals
A pro forma that carries the seller's tax bill forward is not modeling the asset, because in reassess-on-sale and mark-to-market states the bill resets in year one.
The number that decides a loan is neither demand nor supply but the gap between them, measured over the time the subject takes to open and lease up, and a study earns that gap only by enumerating the competitive set, staging the pipeline by probability of delivery and deriving absorption from comparable lease-ups.
A demographic analysis is defensible only when it names the population it uses, discloses the error around it, and projects it from current components of change.
The Primary Market Area is the single most consequential analytical decision in a feasibility study, because the four accepted construction methods applied to the same site produce boundaries that differ by 2x to 3x in addressable population.
A single underwritten DSCR understates default risk, and three methods run together replace it: sensitivity to rank the drivers, breakeven to set the covenant, and Monte Carlo with copula correlation to attach a probability.
Capture rate is derived from the trade area and the demand left after competitive supply is netted out, and a study that cannot show the multipliers cannot defend the number.
A competitor analysis is bankable only when the trade area, the comp set and the forward pipeline are each built from more than one data source and then stress tested.
Spirit Airlines' April 6, 2026 Plan of Reorganization cannot survive the fuel shock it was never stressed against, and whichever way the Chapter 11 resolves, the hotel markets that depend on Spirit's leisure capacity face a measurable demand shock.
Absorption pace is the feasibility input that decides whether a project services its debt before the interest reserve is exhausted, and it has to be presented as base, downside and severe downside scenarios rather than one number.
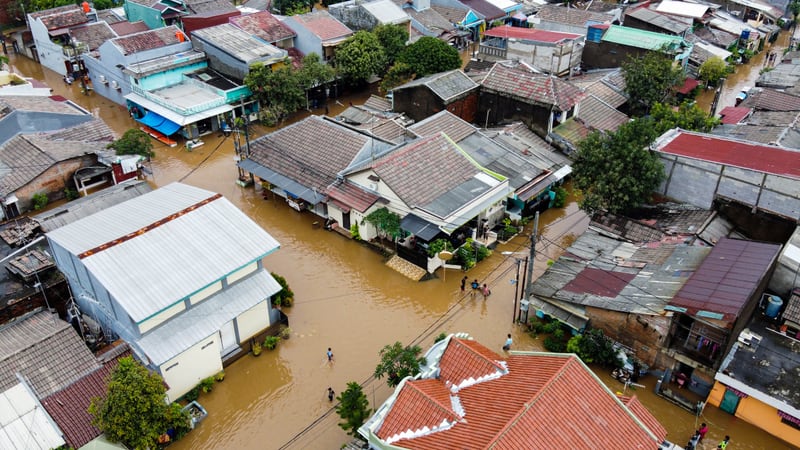
Flood zone and wetland exposure sets project economics before design begins, so the construction premium, the insurance path and the permitting clock all belong in the first week of due diligence.
Seismic risk is one of the most consequential and most underpriced variables in commercial real estate: markets reprice it for a few months after a major earthquake and then revert, while insurance uptake stays low and retrofit compliance runs slowly against long deadlines.
The industries this shock breaks rather than squeezes are the ones carrying both the highest fuel share of cost and the weakest balance sheets going in.
American dialysis is a duopoly built on structural patient captivity and Medicare's categorical ESRD entitlement, and that structure is only now beginning to be tested by antitrust scrutiny, home modalities and new entrants.
The US office market is under severe financial strain but may be bottoming out: the office CMBS delinquency rate reached 12.3% in January 2026, its highest level ever, after standing at roughly 10.2% in January 2025, while the national vacancy rate hit 14.2% in mid-2025 and edged down to about 14.0% by year-end 2025.
What broke investors in 2008 was behavior rather than arithmetic: overconfidence, mispriced risk and borrowed money chasing a price that could only rise.
The U.S. homeowners' insurance market keeps growing through 2030, but the growth comes from higher premiums per policy rather than from more insured homes.
US fertility clinics will keep growing through 2030, but at a slower pace than the past five years, with IVF as the industry's economic engine and private equity consolidating a fragmented field.
Commercial property insurance has repriced permanently, and the recent easing in rates does not reverse the increases already banked into operating budgets.
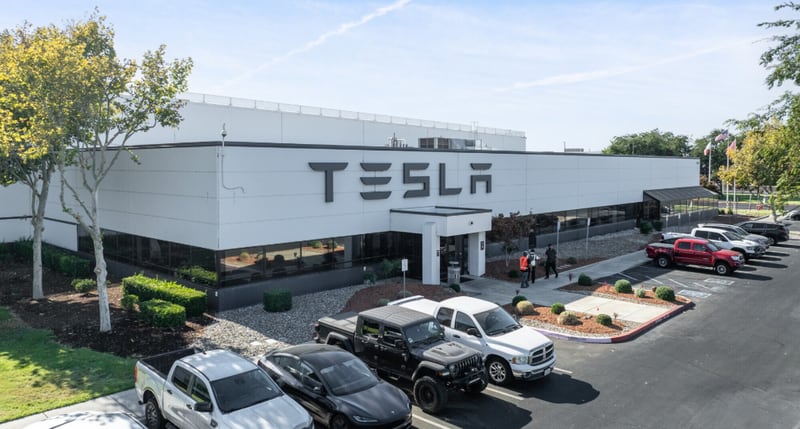
Ford occupies about four times the U.S. real estate Tesla does and runs three to four times more space per worker, a gap that comes from plant age, product mix and who owns the sales network rather than from any single efficiency advantage.
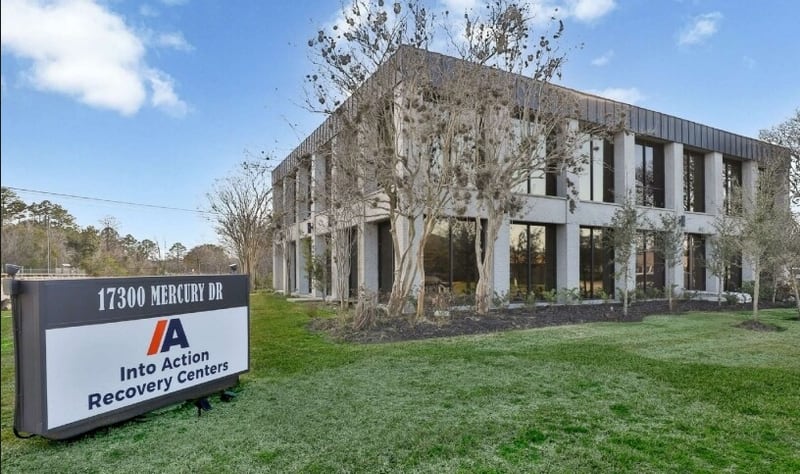
A single-location for-profit rehab clinic is feasible in 2025, but only on modest margins: industry revenue reached an estimated $5.3 billion in 2024 and is projected to reach ~$6.4 billion by 2028, while net profit margins average around 4.2% and MMCG expects them to stay roughly in the 4 to 5% range.
A Phase I Environmental Site Assessment is worth the investment on every commercial real estate deal: it is the recognized way to perform the All Appropriate Inquiries that qualify a buyer for CERCLA's innocent landowner and bona fide prospective purchaser defenses, and lenders will not close without one.
A development pro forma becomes a feasibility study when its cash flows are converted into a yield on cost, a stabilized value, and a spread that can be measured against the market.
NeueHouse failed because a premium clubhouse model built on multi-million-dollar buildouts and hefty long-term leases could not carry its fixed costs once membership growth stalled, and no buyer stepped in as one had in 2020.
Cap rates track the cost of capital and the price of risk rather than nominal Treasury yields, so why rates are moving matters more than how far they move.
GIC has rebuilt its real estate portfolio around logistics and long leases, and its recent activity upgrades asset quality rather than adding floor area.
Brookfield is carrying a diversified portfolio through a hard office cycle by selling more than it buys and keeping capital ready for distressed pricing.
A defensible cap rate or discount rate is calculated from evidence and cross-checked, never picked to hit a value: comparable sales lead, investor surveys, broker opinion and historical performance support, and band of investment, the Gordon growth relation and the lender's DSCR method are used to triangulate.
A credible reconciliation is a weighting argument, not an average: the final value must fall inside the range the approaches indicate and sit closest to the ones the evidence supports.
Blackstone has built its real estate portfolio around industrial and rental housing and kept traditional office and retail to a minor share, and its recent transaction record is a rebalancing rather than a retreat.
Outpatient mental health and substance abuse clinics will keep growing through 2030, but the binding constraint is staffing and the policy environment, not demand.
The stabilized vacancy and credit loss assumption, not the current rent roll, is what decides whether a loan clears its covenants, so the path from in-place to stabilized has to be modeled period by period rather than assumed.
A defensible NOI is one that survives the lender's own recalculation, which means recurring items only, plus a management fee and a replacement reserve whether or not the owner currently pays them.
Reconciliation, not any single approach, is what makes a commercial appraisal usable in a credit file, and an appraisal that averages the three indications is not credible under USPAP.
Direct capitalization and a DCF agree when income is flat and perpetual, and they separate the moment lease rollover, growth or a changed exit cap breaks that assumption.
The proposed anti-dumping duty would roughly double the U.S. shelf price of Italian pasta, and because Italy is the single largest supplier of pasta to the United States, the effect would reach consumers, grocers and domestic producers well beyond the two companies named in the case.
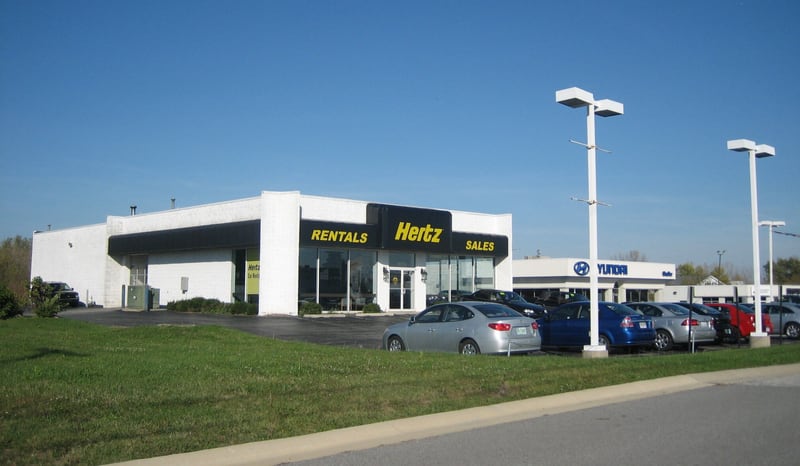
The U.S. car rental industry has settled into a mature, consolidated market that will grow slowly but reliably: revenue of $65.3 billion in 2025 is projected to reach roughly $72.8 billion by 2030, about 2.2% a year, after growth of about 7.8% a year over 2020 to 2025 that reflected the post-COVID rebound.
The U.S. healthcare market will keep growing through 2030, but returns will separate scaled, diversified and technology-enabled providers from Medicaid-dependent and rural operators.
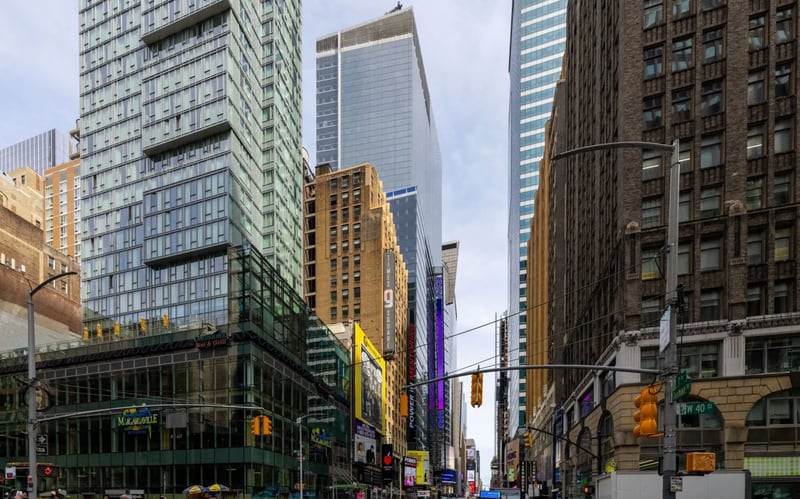
A prime Times Square address gave the 2016 CMBS lenders on 229 W 43rd Street no protection: overleverage and a retail rent roll concentrated in two experiential tenants turned a $470 million appraisal into a $28 million distress sale and a $257 million principal loss.
Capital stayed in the Bay Area through the past year, but it moved into housing, logistics and prime retail while office traded mainly in special situations.
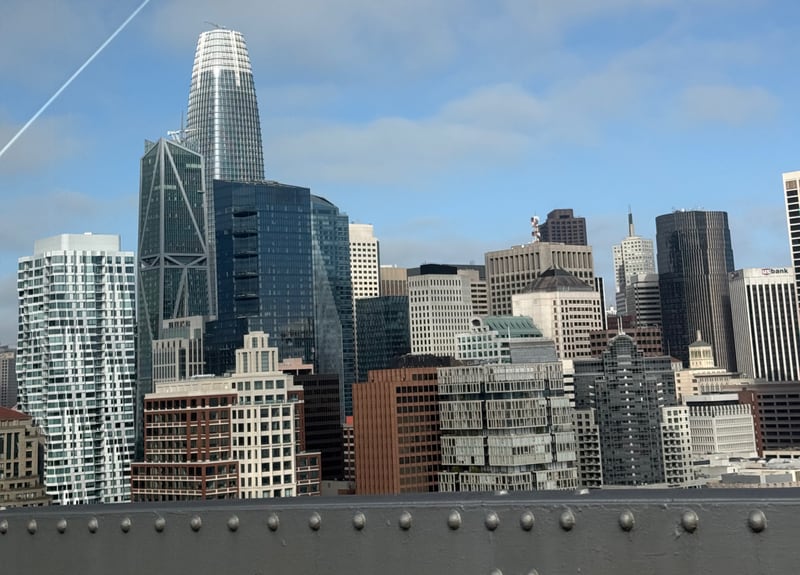
San Francisco's development cycle appears to be at or near bottom, with housing the one segment that still carries demand and office development effectively frozen.
Development in a FEMA flood zone is permitted nearly everywhere except the floodway, provided the structure is elevated or floodproofed and the community participates in the NFIP.
San Francisco's recovery is underway but uneven in mid-2025: office is at a fragile inflection point, multifamily has fully recovered, retail is stabilizing after a downtown shakeout and industrial is still absorbing new lab supply.
A Texas commercial building permit is issued locally, by a city or a county, with state requirements layered on top, and the projects that clear it fastest are the ones that settle zoning, platting, accessibility and code compliance before the application goes in.
As of mid-2025 medical office is the more resilient asset: lower vacancy, steadier rent growth and deeper investor and lender demand than traditional office, which is only beginning to stabilize after a deep downturn.
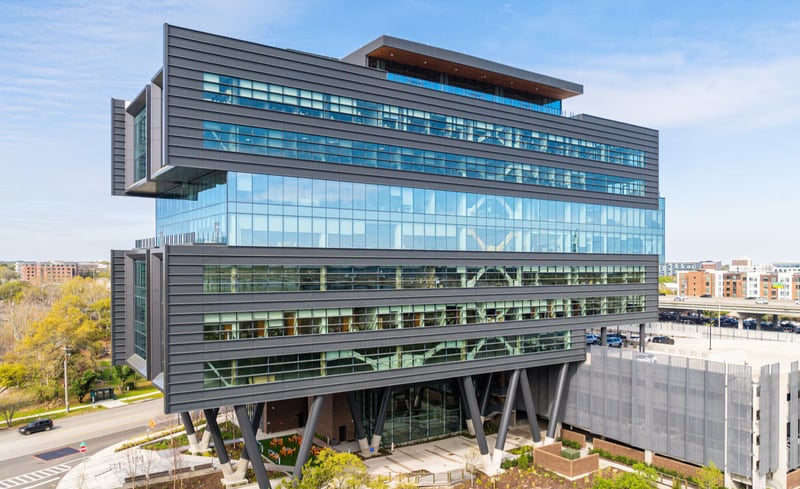
Morrison Yard reached full occupancy at the top of Charleston's rent range, which makes it a case of project execution rather than evidence that office demand has recovered.
The 2025 tariff package is a double-edged sword for U.S. vegetable farming: growers get a brief price tailwind as imports become costlier, but pricier inputs and shrinking overseas demand erode it, and consumers should expect a noticeably steeper produce bill through at least the coming winter.