Summary
JD Sports has built a U.S. business of 2,000+ stores and roughly $5 to 6 billion in annual North American revenue, about 40% of group sales, but its position is not secure: the outcome depends on integrating four acquired banners, coping with a discount-driven young-consumer market, and absorbing tariff volatility. The scale came through acquisitions: Finish Line for about $558 million (over 460 stores), Shoe Palace for $325 million (167 locations), DTLR for roughly $360 million (about 247 shops) and Hibbett Sports for $1.08 billion (1,169 stores across 36 states).
Even so, JD holds only 3 to 4% of a roughly $140 billion U.S. sporting-goods and athleisure market, against about 9% and $13.4 billion in 2024 sales for Dick's Sporting Goods, which now also owns Foot Locker. Nike products make up about 45% of JD's sales and have shown slower growth, while the administration has proposed new 10% duties on imports, so brand concentration and supply costs are the main exposures to watch alongside like-for-like sales and margins.
Written for Lenders and CDCs underwriting athletic or footwear retail tenants, Developers and landlords of mall and small-market retail space, Investors tracking U.S. sporting-goods retail consolidation. 9 minute read.
Key figures
- North America share of JD Sports global revenue
- roughly 40% (on the order of $5 to 6 billion annually)
- industry analystscurrent at publication (February 2026)
- JD Sports U.S. chains annual revenue
- nearly $6 billion a year
- Fortune (January 2026, per the article's sources)current at publication (February 2026)
- Athletic footwear bought in-store
- about 73%
- industry data2022
- Hibbett Sports acquisition
- $1.08 billion for a 1,169-store chain across 36 states
- JD Sports Fashion plc acquisition announcements and Reuters (April and July 2024), per the article's sources2024
- Finish Line acquisition
- about $558 million
- JD Sports Fashion plc, Proposed Acquisition of The Finish Line (March 2018), per the article's sources2018
Updated: Mar 26
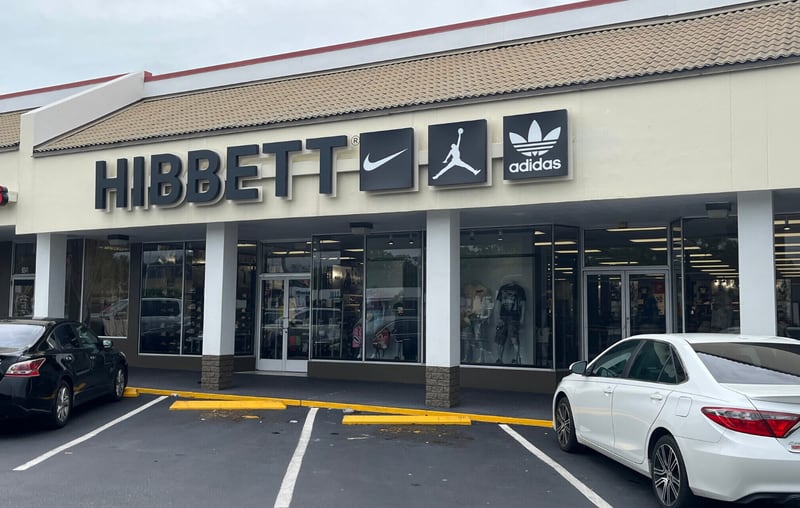
Illustrative picture - HIBBET store (owned by JD Sports)
JD Sports, once a small UK retailer, has quietly transformed into a major player in America’s athletic-fashion landscape. Today its U.S. footprint spans hundreds of brick-and-mortar stores and booming online sales. Industry analysts note that JD’s North American operations now generate on the order of $5 to 6 billion annually – roughly 40% of the company’s global revenue – making the U.S. its largest market. JD controls on the order of 3 to 4% of the U.S. sporting-goods/athleisure market (roughly a $140 billion sector). By comparison, long-time rival Dick’s Sporting Goods pulls in about $13.4 billion in U.S. sales and dominates roughly 9% of the market. JD achieved its rapid U.S. rise through a string of high-profile acquisitions – a strategy that continues to reshape the American sneaker game.
A Storied Expansion: From UK Roots to U.S. Acquisitions
JD Sports began in 1981 in Bury, England, and for decades grew mainly through UK and European stores. Its U.S. ambition launched in 2018 , when JD acquired Indianapolis-based Finish Line for about $558 million. Finish Line brought JD over 460 mall-based stores , giving it immediate national scale. The strategy was unabashedly acquisitive. In December 2020 JD paid $325 million for West Coast chain Shoe Palace, adding 167 locations (specializing in streetwear and a heavily Hispanic customer base). A few months later, in early 2021, JD closed on Baltimore-based DTLR for roughly $360 million, inheriting about 247 urban sports-fashion shops in the Mid-Atlantic and Northeast. More recently (2024), JD spent $1.08 billion on Hibbett Sports, a 1,169-store chain concentrated in smaller markets across 36 states – dramatically boosting JD’s national footprint. In total JD now operates 2,000+ U.S. locations across its banners (Finish Line, Shoe Palace, DTLR, Hibbett, plus a few JD Sports flagship stores), rivaling the store counts of older incumbents. (For context, Dick’s Sporting Goods and Foot Locker combined now exceed 3,200 stores.) JD has said it plans to keep expanding – for example aiming to convert as many Finish Line outlets as possible into JD-branded stores, roughly doubling its “JD Sports” flagship count from today’s ~400 toward 800 in the U.S. .
A Multi-Brand Portfolio Under One Flag
JD’s U.S. presence today is a portfolio of brands , each targeting a segment of the sneaker-obsessed market. The legacy Finish Line chain remains a mall staple under its original name, carrying mainstream athletic footwear and apparel. Shoe Palace (west coast, minority-rich demographics) and DTLR (East Coast urban fashion) cater to niche sneaker subcultures and have their own loyal followings. The acquired Hibbett Sports name brings JD into smaller hometowns, stocking sports equipment and shoes in under-served areas. At the same time JD has begun to establish stores under its own JD Sports banner (notably a New York City flagship opened in 2021), aiming to build brand prestige akin to its European image. Across all brands JD’s U.S. stores are polished, youth-focused environments, typically featuring major athletic labels (Nike, Adidas, etc.), exclusive collaborations, and “street fashion” styles. These chains complement JD’s omnichannel sales: U.S. web and app sales account for a growing share of revenue, especially among younger shoppers. (Industry data show offline retail still dominates U.S. shoe sales – about 73% of athletic footwear was bought in-store in 2022 – but e-commerce is the fastest-growing channel.) MMCG market intelligence notes that JD’s strategy of asset-light mall leases combined with an all-digital shopping experience has thus far outpaced many traditional retailers.
Financial Footing and Key Metrics
Since entering the U.S., JD’s North American segment has contributed a leap in revenue and profit. In Fortune’s analysis, JD’s U.S. chains now pull in “nearly $6 billion a year” . In JD’s latest annual report, the company indicated North America represents about 40% of group sales . By MMCG’s estimate, JD’s U.S. revenue stands in the mid-single-digit billions (for context, global JD Sports sales were forecast around £11.5 billion in 2025). The U.S. business has been growing: JD reported like-for-like sales trends improving in late 2025 after a COVID lull. Gross margins on footwear are healthy (as high as 40 to 50% in normal times), though JD has been discounting more heavily in the current weak consumer climate. Analysts expect the U.S. operations to achieve mid-to-high single-digit operating margins as the acquisition integration progresses. JD’s use of strong cash flow from the UK/Europe helped fund these acquisitions without heavy debt: e.g., Shoe Palace was paid from JD’s cash reserves. With roughly 3,000 U.S. employees just in retail operations (plus central support staff), JD’s American arm is a major workforce and profit center. (For scale: the entire U.S. athletic specialty market is about $140B, and JD’s slice of that is estimated at only a few percent, so growth is still theoretically possible.) MMCG data suggests that JD’s share of U.S. sports/footwear retail may grow by a few basis points each year if it executes on store conversions and omni-channel initiatives.
Retail Landscape: Bricks, Clicks and Competition
The U.S. sneaker retail scene is fiercely competitive. On one side are entrenched giants like Foot Locker and Dick’s Sporting Goods . Foot Locker (including its Champs and Eastbay brands) operated roughly 2,500 stores before its 2025 sale to Dick’s. Dick’s Sporting Goods, with about 885 stores and $13.4 billion in 2024 sales (soon enriched by Foot Locker’s outlets), is now the largest U.S. sports retailer. These rivals compete on scale and have broad product mixes (Dick’s carries everything from hunting rifles to team sports gear). In contrast, JD sticks to footwear, apparel and accessories, focusing on trendy and limited-edition lines. Another challenge is the growing direct-to-consumer (DTC) trend among brands. Nike, for example, is pulling back wholesale relationships: in FY2023 over $21.3B of its $51.2B revenue came through Nike-owned channels (up ~42% of total). In other words, a young shopper may now find “Nike shoes” in a Nike store or online, rather than through Foot Locker or JD. Amazon and Walmart also siphon athleisure demand – Amazon is already the second-largest footwear seller in the U.S. – and these mass channels add price pressure. In specialty retail, smaller chains like Academy Sports + Outdoors and emerging concept stores also nibble market share. Notably, under Armour shifted almost entirely to online and pulled out of many stores in recent years, illustrating the risk that big brands can bypass middlemen. JD’s multi-brand model, however, insulates it somewhat: even if Nike retreats, JD can push other labels or grow its own branded products.
Consumer Trends and Macro Context
Athletic and casual footwear remain strong American fashion – running shoes now account for about 60% of the U.S. footwear market (versus roughly 30% a decade ago). Sports apparel/athleisure is also a hot segment: Americans spent a rapidly rising share of clothing budgets on workout gear, sneakers and streetwear over the past decade. MMCG data show that young consumers (ages 16 to 30) continue to prioritize sneaker brands, driving demand for the latest drops and collaborations. JD CEO Régis Schultz has emphasized this, noting “as soon as you start wearing sneakers, you don’t go back to formal shoes,” and pointing to running-brand opportunities. Nonetheless, near-term headwinds loom. Economic reports indicate JD’s core customer (under-30, often still in school or starting careers) faces rising rents, loans, and budget constraints. In late 2025 JD warned that these young shoppers are under pressure, and the U.S. is currently “a market driven by discounts”. Notably, Nike products (which make up ~45% of JD’s sales) have seen slower growth, suggesting JD may need to diversify brands. On the policy side, trade uncertainty remains a factor: a recent U.S. Supreme Court ruling scrapped large parts of old import tariffs, but the Trump administration quickly proposed new 10% duties on incoming goods. For JD (which imports most merchandise), this means supply costs could still jump unpredictably, an upside-down “relief” that market experts say just adds volatility. Likewise, higher interest rates and inflation have squeezed consumer spending, which may slow growth in 2026 and beyond.
Growth Levers and Risks Ahead
Looking forward, JD’s U.S. outlook hinges on scale, integration and innovation . Key growth levers include: opening more stores (by converting underperforming Finish Lines into JD Sports flagships), expanding e-commerce reach, and tapping new demographics (e.g. deeper penetration in Hispanic and youth markets, where Shoe Palace and DTLR already perform well). JD’s recent move into AI-driven commerce reflects a push to blend digital and physical shopping: U.S. customers can soon search and buy via chatbots (Microsoft’s Copilot, Google Gemini or ChatGPT) from JD’s catalog, potentially speeding checkout and even reallocating store space (15 to 20% currently for cash registers) toward product displays. JD is also experimenting with loyalty programs and in-house brands to boost margins. Geographically, after the Hibbett deal JD could eye adjacent markets (Canada or Mexico) if regulatory and retail conditions allow. However, challenges are real: cultural shifts in fashion, an oversupplied retail mall environment, and the sheer pace of change in youth tastes mean JD must stay agile. On the plus side, JD’s use of off-balance-sheet leases and low fixed-cost expansion (vs. heavy warehouse chains) could allow profitable growth even if sales growth moderates.
In sum, JD Sports has vaulted from a European upstart to a U.S. athleisure heavyweight in a few years, as its carefully carved niche among teen sneakerheads shows no sign of saturation. But future success isn’t guaranteed. Success will depend on how well JD meshes its new brands into a coherent chain, how it navigates an evolving retail ecosystem (online competition and shifting consumer tastes), and how external forces like the economy and trade policy play out. If JD maintains its current momentum, doubling down on its sneaker-centric branding while cautiously managing costs, it could firmly establish itself as a fixture of American sneaker culture. But any misstep (a prolonged consumer slowdown, integration woes, or a failed bet on a trend) could leave it exposed. The counter-example is instructive, because the hundred-year decline of Eddie Bauer shows what happens to an outdoor brand that loses the niche it was built on.
Industry data suggest that JD’s agile, store-light approach gives it runway to keep growing in the U.S., but watchful monitoring of U.S. sales trends, profitability, and the broader retail environment will be critical in the months ahead.
February 22, 2026 by a collective of authors at MMCG Invest, LLC, USDA feasibility study consultants
Sources:
The British retailer riding the wave of America’s always-on sneaker culture - Fortune - 2026-01-27
JD Sports sees profit at lower end of forecasts amid weak demand - Reuters - 2025-11-20 market-e xpectations-2025-11-20/
Britain’s JD Sports launches AI shopping for US customers - Reuters - 2026-01-12 -
Proposed Acquisition of The Finish Line, Inc. - JD Sports Fashion plc - 2018-03-26 -
Acquisition of Shoe Palace in United States - JD Sports Fashion plc - 2020-12-15 -
JD Sports buys Shoe Palace to expand footprint on U.S. West Coast - Reuters - 2020-1
Conditional Agreement for the Acquisition of DTLR - JD Sports Fashion plc - 2021-02-01
Completion of the acquisition of DTLR - JD Sports Fashion plc - 2021-03-18 -
JD Sports to buy Hibbett in $1.08 billion deal - Reuters - 2024-04-23 -
Completion of the acquisition of Hibbett, Inc. - JD Sports Fashion plc - 2024-07-25 -
Dick’s Sporting Goods to buy Foot Locker for $2.4 billion - Reuters - 2025-05-15 -
DICK’S Sporting Goods Completes Acquisition of Foot Locker - DICK'S Sporting Goods - 2025-09-08
NIKE, Inc. Reports Fiscal 2023 Fourth Quarter and Full Year Results - Nike - 2023-06-29
JD Sports Fashion Plc Annual Report & Accounts 2025 - JD Sports Fashion plc - 2025-05-20 -
After court ruling, Trump says US global tariff rate will rise from 10% to 15% - Reuters - 2026-02-21
Hibbett, Inc. Definitive Proxy Statement (Merger) - U.S. Securities and Exchange Commission - 2024-04-23 (filed) -
Hibbett, Inc. Announces Definitive Agreement to be Acquired by JD Sports Fashion plc - Business Wire - 2024-04-23 -
BRS Completes Sale of DTLR Villa, LLC to JD Sports Fashion Plc - PR Newswire - 2021-
JD Sports to deepen US reach with $1bn bid for Hibbett - Financial Times - 2024-04-23
JD Sports Fashion Proposes To Buy Hibbett - The Wall Street Journal - 2024-04-23 -
JD Sports plans to let shoppers buy through AI platforms - The Guardian - 2026-01-12
What JD Sports’ AI Play Means For Retailers - Forbes - 2026-02-04 -
JD Sports to Launch AI Commerce on ChatGPT, Copilot - WWD - 2026-01-12 -
Fitness/Sport Equipment

Michal Mohelsky, J.D., FMVA, Practicing Affiliate of the Appraisal Institute
Principal, MMCG Invest, LLC
Published February 22, 2026. Last updated March 26, 2026. How this analysis was prepared.
Cite this
Michal Mohelsky, J.D., FMVA (2026). JD Sports: The sneaker empire reshaping global athletic retail. MMCG Invest, LLC. https://www.mmcginvest.com/post/jd-sports-the-sneaker-empire-reshaping-global-athletic-retail
Where this leads
Where this goes next
- USDA Feasibility StudyMMCG's feasibility study page for this subject.