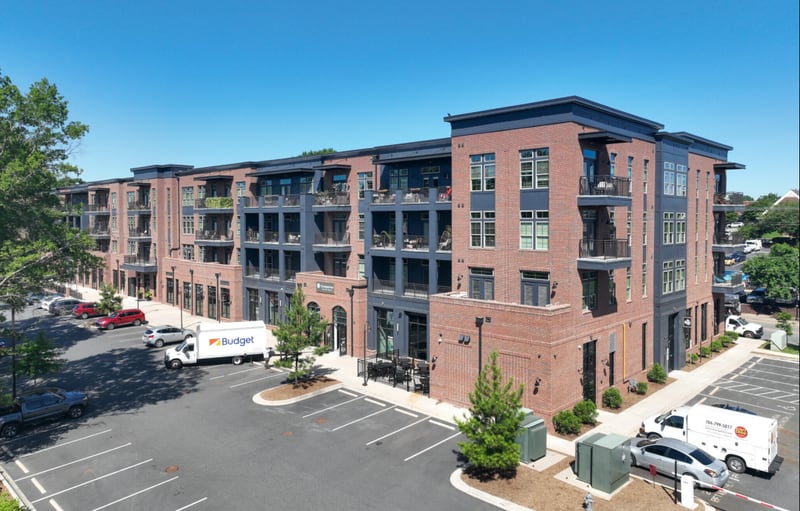
Summary
Charlotte's apartment market has softened under a construction-driven supply wave, and the body concludes that vacancy will stay above the national average through 2025 before fundamentals re-tighten in late 2025 and 2026. As of Q3 2024, metro occupancy was about 93% (roughly 7% vacancy) and the average effective rent was about $1,557 per unit, with 15,527 units delivered over the past 12 months against about 13,100 units absorbed and concessions offered on about 27% of units.
The pipeline remains large at 30,647 units under construction, but permits have eased to about 8,500 year to date, down 16% year over year, which supports the case for slower starts. Outlying submarkets such as Gaston County (94.1% occupancy, no units under construction, $1,404 average rent) look more favorable for new development than core areas like Uptown/South End, where rents reach $2,002 per unit but 4,664 units are under construction. The recommendations are to phase deliveries toward late 2025 or 2026, launch rents slightly below stabilized comparables, and stress-test budgets against rising operating and construction costs.
Written for Developers timing a Charlotte multifamily delivery, Lenders and CDCs underwriting Charlotte apartment projects, Investors evaluating Charlotte submarkets for acquisition or value-add. 4 minute read.
Key figures
- Metro-wide occupancy
- about 93%
- Proprietary Q3 2024 Charlotte metro dataQ3 2024
- Average effective rent
- roughly $1,557 per unit
- Proprietary Q3 2024 Charlotte metro dataQ3 2024
- New units completed
- ~15,527
- Proprietary Q3 2024 Charlotte metro datapast 12 months to Q3 2024
- Units under construction
- ~30,650 units
- Proprietary Q3 2024 Charlotte metro dataQ3 2024
- Building permits issued year-to-date
- ~8,500
- Proprietary Q3 2024 Charlotte metro datayear-to-date 2024
- Units offering concessions
- about 27% of units
- Proprietary Q3 2024 Charlotte metro datalate 2024
Updated: Mar 28
Charlotte, NC Multifamily Market Outlook (2025 to 2026)
Market Fundamentals (Current Conditions): Charlotte’s apartment market has softened after a construction-driven expansion. By Q3 2024 the metro-wide occupancy was about 93% (implying ~7% vacancy), down from ~95 to 96% earlier in the cycle. The average effective rent was roughly $1,557 per unit ($1.62/ft²) . In the past 12 months ~15,527 new units were completed against ~13,100 units of absorption, so net deliveries have modestly outpaced leasing. Meanwhile, operating expenses have been under pressure: property taxes, insurance, and maintenance costs have all risen with inflation. These cost trends (and higher vacancies) will squeeze net operating income in the near term.
| Metric | Charlotte MSA (Q3 2024) |
|---|---|
| Total Inventory | 237,707 units |
| Occupancy (Vacancy) | 93.0% (7.0%) |
| Avg. Effective Rent | $1,557/unit ($1.62/ft²) |
| Deliveries (Past 12 mo) | 15,527 units |
| Under Construction | 30,647 units |
Vacancy Trends: A rigorous market and site analysis can help investors identify pockets of resilience within this shifting landscape. Vacancy rose in late 2024 as nearly 16,000 new units hit the market, pushing concessions on about 27% of units. Looking forward, national forecasts project metro vacancy peaking around 6.25% in early 2025 before easing back toward 6.0% by year-end. Charlotte’s elevated pipeline suggests its vacancy may remain above the national average through 2025 before stabilizing in 2026, absorption patterns that align with the broader national multifamily outlook through 2030 .
Rent Growth Outlook (2025 to 2026): After flat-to-negative rent growth late in 2024, Charlotte rents are expected to see only modest increases through 2025. National rent growth forecasts of ~2.0 to 2.5% in 2025 imply Charlotte may lag initially-likely flat or slight declines in early 2025-before turning positive in late 2025 as absorption rebounds. By 2026, with supply growth slowing and job growth remaining healthy, rents should resume a more normalized upward trend, a rent basis that remains a fraction of comparable product in gateway markets like New York .
Submarket Dynamics & Strategic Opportunities:
Undersupplied Outlying Submarkets: Gaston County/Concord and Lake Norman (Mooresville/Statesville) feature occupancies above 94% with minimal new pipelines. These areas offer attractive development opportunities with less competition and still-solid rents (~$1,400 to 1,450 per unit).
Balanced/High-Demand Cores: Uptown/South End and North Charlotte command high rents ( ~$2,000 and ~$1,500 per unit, respectively) but face very large pipelines (4,500 to 4,700 units under construction). Luxury projects here can succeed with differentiated amenities, but timing and phased absorption strategies are critical to avoid lease-up pressure.
Overbuilt/Transitional Areas: East Charlotte and University City have seen negative net demand against growing supply, leading to higher concessions and rent pressure. New developments in these pockets should be approached with caution or targeted on value-add repositioning rather than ground-up luxury builds.
| Submarket | Occ. % | Pipeline (U/C) | Avg. Rent/unit |
|---|---|---|---|
| Uptown/South End | 92.4% | 4,664 units | $2,002 |
| North Charlotte | 92.9% | 4,547 units | $1,497 |
| Southwest Charlotte | 93.5% | 5,972 units | $1,500 |
| Gaston County (outlying) | 94.1% | 0 units | $1,404 |
| Concord/Kannapolis | 93.8% | 2,570 units | $1,447 |
| East Charlotte | 92.7% | 1,951 units | $1,402 |
Supply, Demand & Forecasts: Developers seeking financing for projects in this pipeline should consider an SBA feasibility study to strengthen their underwriting package. The Charlotte pipeline remains formidable at ~30,650 units under construction. Building permits have eased (~8,500 issued year-to-date, down 16% YoY), suggesting new starts may moderate. If annual completions fall to 10 to 12K in 2025 to 26 while absorption normalizes around the same level, the market should gradually re-tighten by late 2025.
Actionable Recommendations:
Unit Mix & Product: In underserved outlying areas, prioritize mid-market 2 to 3 BR units to match family demand. In core submarkets, differentiate luxury product with high-end finishes and consider concessions to accelerate lease-up.
Pricing Strategy: Launch new projects with rents set slightly below comparable stabilized assets to secure early occupancy, then escalate to market rates.
Delivery Timing: Phase or delay projects slated for early 2025 delivery to avoid peak vacancy; target late-2025/2026 completion windows to capitalize on tightening fundamentals.
Financing & Partnerships: For broader context on capital flows, our mid 2025 New York multifamily market report offers a comparative view of institutional investment trends in the Southeast corridor. Lock in favorable financing rates now. Consider public–private partnerships, tax credits, or alternative debt sources to mitigate rising cap‐rate pressure, legislative interventions that neighboring states like Florida have pursued through density and zoning reforms .
Risks:
Persistent Oversupply in key submarkets could force deeper concessions.
Financing Constraints from higher rates and tighter underwriting may delay or downsize projects.
Economic Slowdown, particularly in finance/tech-could weaken job growth and reduce net migration-though migration-driven rental markets like Idaho demonstrate the persistence of domestic relocation trends.
Cost Inflation in construction and operations may compress returns unless project budgets are stress-tested.
For a detailed assessment of multifamily development, see MMCG's multifamily feasibility study .
Sources: Proprietary Q3 2024 Charlotte metro data on occupancy, rents, deliveries, and pipelines; national multifamily market forecasts for rent growth and vacancy trends through 2026.
April 28, 2025, by Michal Mohelsky, J.D., principal of MMCG, multi-family feasibility study consultant
Sources:
Fannie Mae U.S. Economic and Multifamily Housing Outlook, January 2025
CBRE U.S. Multifamily Market Outlook Q1 2025
JLL U.S. Apartment Insights Q1 2025
Yardi Matrix National Apartment Report, April 2025
Freddie Mac Multifamily Market Commentary Q1 2025
NMHC 2025 Multifamily Housing Market Trends Report
ULI Emerging Trends in Real Estate 2025: Multifamily Sector Analysis
Multi Family
Michal Mohelsky, J.D., FMVA, Practicing Affiliate of the Appraisal Institute
Principal, MMCG Invest, LLC
Published April 28, 2025. Last updated March 28, 2026. How this analysis was prepared.
Cite this
Michal Mohelsky, J.D., FMVA (2025). Charlotte, NC Multifamily Market Outlook (2025 to 2026). MMCG Invest, LLC. https://www.mmcginvest.com/post/charlotte-nc-multifamily-market-outlook-2025-2026
Work behind the citation
Where this goes next
- SBA Feasibility StudyMMCG's feasibility study page for this subject.