Summary
Carraway RV & Boat Storage shows what a low-leverage, purpose-built RV and boat storage facility can do: rent per square foot rising every year, occupancy steady at 97%, and debt service coverage far above lender thresholds. The 70,893 SF facility in Magnolia, TX carries a $2.2 million fixed-rate CMBS loan at 4.15%, placed in May 2021 at 62% LTV against a $3.55 million appraisal and roughly 48% loan-to-cost on a $4.6 million project basis.
Base rent grew from $4.69/SF in 2021 to $5.35/SF in Q1 2024, a 14% compound lift, while NOI climbed from $2.94/SF to $3.41/SF. NOI coverage now sits at 1.88×, a 63% debt service cushion, with the expense ratio held in the mid-30% range.
Written for Lenders underwriting RV and boat storage loans, Developers and sponsors of outdoor storage facilities, Investors evaluating self-storage cash flows. 5 minute read.
Key figures
- Permanent CMBS loan
- $2.2 million (62% LTV on a $3.55 million as-complete appraisal)
- CMBS, per the article's sources lineMay 2021
- Implied loan-to-cost ratio
- near 48%
- CMBS, per the article's sources lineMay 2021 origination
- Base rent per square foot
- $5.35/SF (up from $4.69/SF in 2021)
- CMBS, per the article's sources lineQ1 2024
- Actual occupancy
- 97%
- CMBS, per the article's sources line2021 to Q1 2024
- NOI per square foot
- $3.41/SF (up from $2.94/SF)
- CMBS, per the article's sources lineQ1 2024
- Operating expense growth per square foot
- ~12%
- CMBS, per the article's sources line2021 to Q1 2024
Updated: Mar 26
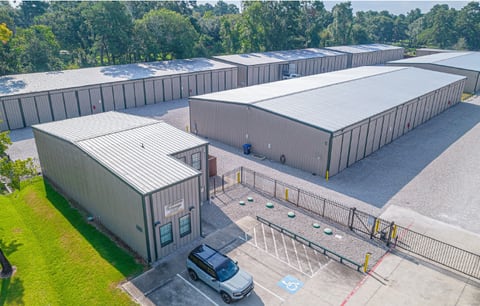
Carraway RV & Boat Storage, Magnolia, TX
In this article, we will examine a typical RV & boat storage facility and analyze its financial performance, expenses, and profitability. Our case study focuses on Carraway RV & Boat Storage-a modern outdoor storage asset-and digs into its revenue trends, cost structure, and debt‐service metrics.
1. Introduction & Development Timeline
Carraway RV & Boat Storage, a purpose-built outdoor self-storage facility, opened its doors in early 2018 in Magnolia, TX. Conceived to capture growing demand for outdoor vehicle storage in the northwest Harris County submarket, the project comprises:
70,893 SF of gated, aggregate-surfaced storage bays
A 5-acre land platform zoned and improved for RV/boat storage
Ancillary office/amenity building and paved ingress/egress lanes
From the outset, the developer pursued a capital-efficient structure to balance risk and return. In May 2021, a permanent CMBS loan of $2.2 million was placed, sizing the debt at 62% LTV based on a $3.55 million as-complete appraisal. Given an acquisition or total project basis of approximately $4.6 million , the implied loan-to-cost ratio stood near 48% , with roughly $2.4 million of sponsor equity deployed.
2. Capital Structure & Credit Profile
| Loan Attribute | Detail |
|---|---|
| Origination Amount | $2,200,000 |
| Origination LTV (Appraisal) | 62% |
| Implied LTC (Project Cost) | ~48% (based on $4.6 M cost) |
| Current Balance | $2,048,473 |
| Interest Rate | 4.15% (fixed) |
| Origination Date | May 1, 2021 |
| Maturity Date | May 6, 2031 |
| Remaining Amortization | 313 months |
| 2023 NOI / Debt Service | $235,603 / $128,362 → 1.84× DSCR |
| Pay Status | Performing |
MMCG Insight: With a low‐leverage capital stack (LTC < 50%) and a seasoned, fixed-rate CMBS loan featuring a healthy 1.8×+ DSCR buffer, Carraway stands in a defensible position against rising rates and potential market dislocations.
3. Revenue Trends & Income-Per-Square-Foot Analysis
Over the past four years, Carraway’s base rent per square foot has exhibited a consistent upward trajectory, reflecting both tightening market supply and active yield-management by the operator.
| Year / Period | Base Rent ($/SF) | Other Income ($/SF) | Effective Gross Income ($/SF) |
|---|---|---|---|
| 2021 (YE) | 4.69 | 0.00 | 4.69 |
| 2022 (YE) | 4.97 | 0.01 | 4.98 |
| 2023 (YE) | 5.29 | 0.02 | 5.31 |
| Most Recent (Q1 ’24) | 5.35 | 0.02 | 5.37 |
| Underwritten (Sep 2021) | 5.05 | 0.64 (Vacancy Credit) | 5.69 |
Base Rent Growth: From $4.69/SF in 2021 to $5.35/SF in Q1 2024, Carraway achieved a 14% compound lift in base revenues.
Other Income: Nominal “other” dollar contributions (late fees, admin charges) rose from zero to $0.02/SF; parking income remains immaterial.
Vacancy & Collection Reserves: The underwritten model built in a 12.7% loss assumption ($0.64/SF), but actual occupancy has held at 97% , compressing realized loss‐to‐lease below budget and boosting realized EGI.
MMCG Insight: The glide-path of base rent enhancement, paired with occupancy retention above 95%, underscores the facility’s high-barrier, niche positioning and the operator’s dynamic pricing capability.
4. Operating Expense Breakdown
A deep-dive into OPEX highlights several levers of margin management and cost pressures:
| Expense Category | 2021 | 2022 | 2023 | Q1 ’24 | Underwritten |
|---|---|---|---|---|---|
| Real Estate Taxes | 1.01 | 0.50 | 0.50 | 0.49 | 0.43 |
| Property Insurance | 0.17 | 0.19 | 0.28 | 0.28 | 0.16 |
| Utilities | 0.12 | 0.15 | 0.18 | 0.18 | 0.12 |
| Repairs & Maintenance | 0.07 | 0.11 | 0.14 | 0.14 | 0.08 |
| Management Fees | 0.15 | 0.25 | 0.27 | 0.27 | 0.22 |
| Payroll & Benefits | 0.01 | 0.32 | 0.37 | 0.31 | 0.12 |
| Advertising & Marketing | 0.01 | ||||
| Professional Fees | 0.07 | 0.08 | 0.08 | 0.11 | |
| General & Administrative | 0.15 | 0.17 | 0.17 | 0.18 | 0.19 |
| Total Operating Expenses | 1.75 | 1.77 | 1.99 | 1.96 | 1.33 |
| Expense Ratio | 37.35% | 35.56% | 37.44% | 36.46% | 23.41% |
Taxes & Insurance: After a spike in 2021 taxes (post-build assessment), tax load stabilized at $0.50/SF; insurance has ratcheted up in 2023 as carriers price specialty risk.
Maintenance & Utilities: Reflects normalizing routine repairs, gate/lock servicing, and higher utility tariffs; repairs grew from $0.07 to $0.14/SF.
Personnel & Management: Management fees and on-site staffing costs (payroll & benefits) now account for ~0.58/SF, versus near zero in 2021 as leasing office staffing was scaled up.
Efficiency Lens: Even with cost inflation, OPEX/SF has only crept ~12% from 2021 to Q1 2024, while EGI/SF has grown ~14%, preserving mid-30% expense ratio margins.
MMCG Insight: The profile exhibits operational leverage, where revenue growth outstrips cost inflation-an archetype of a high-fixed cost, high-margin asset class. Focus areas for further margin expansion include proactive tax appeals, cost-sharing for utilities (e.g., solar investment), and tech-enabled self-service management.
5. Net Operating Income & Capital Coverage
| Metric | 2021 | 2022 | 2023 | Q1 ’24 |
|---|---|---|---|---|
| Effective Gross Income ($/SF) | 4.69 | 4.98 | 5.31 | 5.37 |
| Total OPEX ($/SF) | 1.75 | 1.77 | 1.99 | 1.96 |
| NOI ($/SF) | 2.94 | 3.21 | 3.32 | 3.41 |
| Capital Expenditures ($/SF) | 0.00 | 0.10 | 0.10 | 0.10 |
| Net Cash Flow ($/SF) | 2.94 | 3.11 | 3.22 | 3.31 |
| NOI DSCR (×) | 1.62 | 1.77 | 1.84 | 1.88 |
| Net CF DSCR (×) | 1.62 | 1.72 | 1.78 | 1.83 |
| Occupancy (%) | 97.0 | 97.0 | 97.0 | 97.0 |
NOI Growth: A steady climb from $2.94/SF to $3.41/SF (16% increase) underscores the property’s healthy margin improvement.
DSCR Cushion: Current NOI coverage sits at 1.88× , well above typical lender thresholds (1.20 to 1.25×), delivering a 63% debt service cushion .
Capital Reserves: A recurring $0.10/SF capex reserve ensures doors and gates remain in turnkey condition, underpinning long-term value.
MMCG Insight: The combination of predictable cash flows, robust DSCR, and resilient occupancy creates a defensible investment thesis-self-storage remains counter-cyclical in economic downturns, delivering steady yield to stakeholders.
6. Strategic Takeaways & Value-Creation Opportunities
Margin Enhancement: Pursue further expense rationalization via tax appeals, bulk insurance procurement, and solar-offset utility savings.
Revenue Upside: Explore remote kiosks, dynamic pricing software, and ancillary service add-ons to lift other income above the token $0.02/SF.
Refinancing Potential: With LTV at ~61% and strong DSCR, the facility is well-positioned for a rate arbitrage refinance or mezzanine wave to monetize basis.
Portfolio Scalability: Leverage operating platform to roll out multiple facilities in adjacent infill submarkets, capturing scale economies in management and procurement.
7. Conclusion
Carraway RV & Boat Storage exemplifies a modern self-storage playbook: strategic site selection, disciplined capital structure, and operational rigor have combined to drive consistent year-over-year growth in revenue per square foot, maintain sub-40% expense ratios, and deliver a debt service coverage well above market covenants. As the property matures, value-creation levers-particularly in cost optimization and digital customer experience-promise to further elevate returns, cementing its standing as a high-quality, cash-flowing real asset. RV and boat storage development economics are explored further in our RV storage feasibility study .
May 15, 2025, by a collective of authors of MMCG Invest, LLC, RV & Boat storage feasibility study consultants
Sources: CMBS, Montgomery County Assessor
Michal Mohelsky, J.D., FMVA, Practicing Affiliate of the Appraisal Institute
Principal, MMCG Invest, LLC
Published May 15, 2025. Last updated March 26, 2026. How this analysis was prepared.
Cite this
Michal Mohelsky, J.D., FMVA (2025). Case Study: Financial Analysis of a Modern RV & Boat/Self-Storage Facility. MMCG Invest, LLC. https://www.mmcginvest.com/post/case-study-financial-analysis-of-a-modern-rv-boat-self-storage-facility
Where this goes next
- Self Storage Feasibility StudyMMCG's feasibility study page for this subject.